

Blogs
Navigating the Nervous System Medications Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
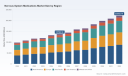
The global nervous system medications market has entered a phase of sustained expansion, with total revenue projected to climb from approximately $137.6 billion in 2025 to over $222 billion by 2032, reflecting a compound annual growth rate of 7.12 percent. This trajectory underscores a structural shift in how neurological and psychiatric conditions are diagnosed, treated, and managed across healthcare systems worldwide. The growth is not merely incremental; it signals deepening clinical reliance on targeted pharmacotherapies, expanding indication coverage, and increasing integration of nervous system treatments into broader chronic care pathways. As healthcare providers confront growing caseloads of neurodegenerative, psychiatric, and pain-related conditions, pharmaceutical stakeholders are recalibrating portfolios to capture value across both established and emerging therapeutic areas.
Despite the favorable macro trajectory, the sector faces several pivotal challenges that will shape competitive outcomes over the next decade. First, the tension between innovation and patent cliffs remains acute. Recent exclusivity losses on widely prescribed anti-epileptic and psychiatric agents have accelerated generic infiltration, compressing margins for originator manufacturers while simultaneously expanding affordable access for patients and payers. Second, reimbursement architectures are undergoing recalibration. Payers are increasingly scrutinizing real-world effectiveness, pharmacoeconomic outcomes, and differentiated clinical value, particularly for high-cost neurology therapies and specialty injectables. This environment rewards manufacturers that can demonstrate measurable health economic benefits rather than relying solely on clinical efficacy narratives. Third, supply chain dependencies continue to introduce volatility. The concentration of active pharmaceutical ingredient sourcing, particularly for complex nervous system compounds, across select contract manufacturing ecosystems has highlighted the need for geographic diversification, inventory resilience, and robust quality oversight. These dynamics collectively demand a more agile, data-informed approach to portfolio strategy, pricing, and market access.
PW Consulting
Key Drivers Shaping Market Evolution
Technological and scientific breakthroughs are redefining the therapeutic ceiling for nervous system disorders. The emergence of first-in-class mechanisms that target peripheral pain pathways without engaging opioid receptors illustrates a broader industry pivot toward safer, mechanism-driven interventions. Concurrently, advances in monoclonal antibody platforms and neurodegenerative disease modulation are expanding the treatment frontier for conditions historically considered difficult to modify pharmacologically. These scientific strides are enabling developers to pursue earlier intervention, more precise patient stratification, and formulations that improve adherence through reduced dosing frequency or alternative delivery routes. For commercial teams, the implication is clear: therapeutic differentiation increasingly hinges on mechanism novelty, convenience, and aligned diagnostic ecosystems rather than incremental efficacy gains alone.
Worldwide Sedative-Hypnotic Drug Market
Regulatory environments are simultaneously reshaping market entry and lifecycle management. Regulators have maintained a relatively active approval cadence, with notable clearances spanning acute pain management, advanced Parkinson’s motor fluctuation therapies, and expanded indications for neuroimmunological conditions. At the same time, agencies are embedding more nuanced post-market requirements, including genetic or biomarker-based testing considerations, pediatric expansion pathways, and real-world evidence expectations. These regulatory nuances create both opportunity and complexity. Companies that proactively design development programs with regulatory and market access requirements in mind are gaining faster, more defensible commercial launches, while those that treat approval as an endpoint rather than a commercial starting point risk under-monetizing valuable assets.
On the demand side, patient and provider behavior is evolving in ways that favor targeted CNS therapeutics. Growing awareness of mental health conditions, broader screening initiatives, and destigmatization efforts are expanding treatment-seeking behavior across psychiatric indications. In neurology, clinicians are increasingly prioritizing therapies that reduce caregiver burden, minimize administration friction, and support long-term disease management. This demand shift is particularly pronounced in outpatient and community care settings, where ease of use, tolerability, and predictable supply are decisive adoption factors. At the same time, healthcare systems are under pressure to control total cost of care, driving preference for treatments that can reduce hospitalizations, emergency interventions, or downstream complications.
Cost structure and supply dynamics complete the driver quartet. Nervous system product portfolios remain sensitive to raw material availability, specialty formulation requirements, and manufacturing scale-up timelines. Regional concentration in active ingredient production has created pockets of exposure, prompting manufacturers to reassess dual-sourcing strategies, technology transfer readiness, and inventory buffers. At the same time, the interplay between branded innovation and generic entry is restructuring profitability across drug classes. Market participants are increasingly balancing portfolio mix between protected innovation, lifecycle management, and generic or biosimilar positioning to sustain revenue resilience through competitive transitions.
Competitive Landscape and Leading Strategies
The competitive field in nervous system medications is characterized by a mix of large diversified pharmaceutical companies, focused neurology and psychiatry specialists, and generic manufacturers with substantial distribution reach. This structure creates a fragmented yet strategically layered environment where value capture depends on therapeutic focus, patent positioning, and market access execution. Leading players are not competing on the same axis; instead, they are differentiating through portfolio concentration, mechanism leadership, and lifecycle management agility.
Worldwide Central Nervous System (CNS) Stimulants Market
Several strategic patterns stand out among top competitors. Large diversified companies are leveraging neuroscience pipelines alongside broad commercial infrastructures to cross-sell into adjacent therapeutic areas and maintain payer relationships across multiple categories. Their advantage lies in scale, regulatory experience, and the ability to fund long-cycle neurodegenerative and neuroimmunological programs. Focused neurology and psychiatric specialists, by contrast, are pursuing sharper differentiation through niche indications, specialized delivery formats, and concentrated medical affairs engagement. These companies often move faster in targeted disease areas and build deep clinical credibility that supports premium positioning in specific segments. Generic and broad portfolio manufacturers continue to play a critical role in expanding access and managing cost pressure, particularly as exclusivity windows close on established products. Their strategic emphasis typically centers on supply reliability, formulation breadth, and competitive pricing across retail and institutional channels.
Recent commercial and regulatory activity illustrates how these strategies are unfolding in practice. The approval of a first-in-class non-opioid peripheral pain mechanism reflects the industry’s push to reduce opioid reliance while addressing acute pain with a differentiated pharmacological approach. In advanced Parkinson’s disease, new subcutaneous therapy options demonstrate continued investment in improving motor fluctuation management and patient convenience. Expanded indications in neuroimmunology and early symptomatic Alzheimer’s therapies highlight how incumbents are extending franchise value through lifecycle refinement and geographically staggered regulatory launches. At the same time, exclusivity changes affecting certain anti-epileptic and psychiatric agents are reshaping competitive intensity in those categories, forcing originators to plan for volume transitions and generic entrants to compete on distribution strength and cost efficiency.
The market structure is evolving along three interlocking trends. Consolidation remains relevant for players seeking scale in commercialization, supply chain control, or pipeline breadth, especially where therapeutic areas require sustained investment and multi-market execution. Differentiation is intensifying as mechanism innovation, delivery innovation, and diagnostic alignment become more central to market access conversations. New and emerging entrants are finding room in specialized indications, novel pain pathways, and psychiatric formulations where focused development can outperform broad but diffuse strategies. The result is a market in which strategic positioning matters as much as scientific merit: companies that clearly define the patient population, value proposition, and reimbursement narrative they are pursuing are better equipped to convert clinical progress into durable commercial outcomes.
Forward Outlook: Trends Defining the Next 3 to 5 Years
Looking ahead, one of the most consequential trends will be the continued shift toward mechanism-specific and non-opioid pain management strategies. As clinical and regulatory momentum builds around peripheral-targeted interventions, the acute and chronic pain segments are likely to experience a gradual but meaningful rebalancing away from traditional opioid-centric prescribing. Commercial winners in this space will be those that can pair differentiated pharmacology with clear safety positioning, practical dosing, and integration into surgical and emergency care pathways. A second major trend will be the broader adoption of neurodegenerative and neuroimmunological therapies as disease-management staples rather than niche options. With approvals and indication expansions advancing in conditions such as early symptomatic Alzheimer’s disease and generalized myasthenia gravis, neurological care is increasingly moving toward earlier diagnosis, biomarker-informed treatment selection, and longer-duration therapy management. This shift creates opportunities for manufacturers and service providers that can support diagnostic workflows, adherence infrastructure, and specialty distribution.
A third trend will be increasing segmentation within psychiatric and neurological prescribing driven by tolerability, administration preference, and health economic considerations. As payers and providers compare alternatives more rigorously, value will accrue to therapies that offer measurable advantages in adherence, side-effect profiles, or total cost-of-care impact. This environment favors portfolio strategies that are explicit about which clinical and economic problems they solve, rather than competing solely on broad category presence. At the same time, uncertainty persists. Patent expirations will continue to redraw competitive boundaries, reimbursement pressure may accelerate pricing negotiation and value-based contracting, and supply chain vulnerabilities could disrupt product availability if not proactively managed. Market participants should therefore treat resilience, evidence generation, and access strategy as core commercial capabilities rather than supporting functions.
Strategic Implications for Decision-Makers
For manufacturers, the priority is to sharpen therapeutic positioning around clearly defined patient outcomes and access-enabling evidence. Investments in differentiated mechanisms, convenient delivery, and robust real-world data generation are likely to yield stronger launch momentum and more defensible pricing positions, especially in categories where generic competition and reimbursement scrutiny are intensifying. For investors, the most attractive opportunities will be found where scientific differentiation, regulatory timing, and market access readiness converge. Due diligence should focus not only on clinical promise but also on exclusivity windows, lifecycle planning, supply chain exposure, and the likelihood of reimbursement alignment in target markets. For procurement and supply chain leaders, the emphasis should shift toward multi-source readiness, demand forecasting for specialty nervous system products, and supplier diversification that reduces concentration risk without sacrificing quality or continuity.
Across all roles, the strategic value of granular market intelligence is rising. Broad category growth signals are useful for direction, but durable decisions depend on segment-level dynamics, competitive timing, regional access conditions, and product-level lifecycle trajectories. Stakeholders seeking to translate these trends into actionable portfolio, investment, or procurement decisions can benefit from deeper segmentation detail, competitive scenario mapping, and tailored market access analysis that aligns with specific strategic objectives.
For detailed analysis of this topic, please visit the official page: Worldwide Nervous System Medications Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Shifts and Commercial Opportunities in the Global Dairy Logistics Market
Market Status and Core Challenges
The worldwide dairy logistics market continues its steady expansion, with revenue moving from approximately $21.4 billion in 2023 to a projected $24.5 billion in 2025, and forecast to approach $39.9 billion by 2032. This trajectory reflects a compound annual growth rate of 7.2% across the 2026–2032 forecast period, signaling sustained investment in temperature-controlled movement, storage, and value-added handling of dairy products. Growth is not uniform across activity types or end products, but the overall direction remains clear: dairy supply chains are becoming longer, more regulated, and more dependent on precise thermal management as consumption habits and sourcing footprints diversify.
Several structural challenges are testing the sector’s resilience. First, temperature integrity across multimodal journeys remains a persistent operational friction point. Dairy shipments frequently traverse refrigerated trucking, cold storage nodes, and ocean or air freight legs, and any deviation can trigger rapid quality degradation, retail rejection, or regulatory non-compliance. The operational burden is amplified when shipments cross jurisdictions with different monitoring and documentation expectations, forcing logistics providers to standardize validation protocols while maintaining flexibility at regional nodes. In practice, this means cold chain performance is increasingly tied to data continuity, equipment reliability, and handler training, not merely to the presence of refrigeration assets.
Second, packaging and transport equipment costs are introducing new volatility into dairy logistics planning. Dairy transport relies heavily on specialized containers, intermediate bulk containers, and pallets engineered to withstand repeated cold cycles while meeting hygiene standards. When resin pricing and manufacturing capacity shift, operators face cost adjustments that are difficult to pass through quickly, especially in contract-heavy lanes. Procurement teams are therefore being pushed to evaluate packaging durability, reuse cycles, and material sourcing as part of logistics cost management rather than treating them as static inputs.
Third, workforce availability and labor economics are reshaping service design. Long-haul refrigerated routes, particularly those carrying dairy across extended distances, depend on skilled drivers and disciplined handling procedures. Wage pressure in reefer segments has become a meaningful component of operating cost, encouraging carriers and logistics managers to rethink route consolidation, asset utilization, and automation where feasible. The challenge is not simply finding labor; it is aligning service frequency, transit windows, and handling complexity with sustainable cost structures. These pressures are not stopping growth, but they are raising the bar for execution quality and forcing operators to demonstrate measurable cold chain reliability rather than simply capacity availability.
Pharmaceutical Logistics Market
Key Growth Drivers
Technological innovation in temperature control and shipment visibility is becoming a central driver of dairy logistics performance. Real-time monitoring hardware, smarter reefer container controls, and integrated telemetry are reducing the risk window during long-distance transport and storage. For dairy products, where temperature excursions can rapidly alter texture, shelf life, and safety parameters, the value of continuous data is no longer theoretical. Recent expansions in reefer capacity paired with live monitoring for dairy exports between Europe and Asia illustrate how carriers are bundling physical capacity with digital assurance. Similarly, the introduction of traceability-oriented reefer platforms indicates a broader shift: shippers are looking for logistics partners that can provide auditable temperature records alongside movement updates, especially when products cross multiple regulatory zones or feed into retail and food-service channels with strict freshness expectations.
Policy and regulatory environments are also reshaping cold chain requirements. Dairy logistics is increasingly governed by mandates that formalize temperature recording, storage practices, and packaging standards. In Europe, refrigerated transport of dairy products above certain temperature thresholds must now be supported by compliant recording devices, turning temperature documentation into a baseline expectation rather than a premium service. At the same time, packaging-related legislation in key markets is nudging operators toward recycled and lower-impact materials for dairy transport packaging. These rules raise the compliance floor, but they also reward operators that can standardize monitoring practices across lanes and proactively adapt packaging strategies. For shippers, the practical implication is that regulatory readiness is now part of logistics suitability: a provider that cannot demonstrate consistent documentation or packaging alignment may face friction in regulated markets regardless of transit speed.
Worldwide Agricultural Logistics Market
Demand-side shifts are altering how dairy is sourced, stored, and moved. Consumer preferences increasingly favor fresh, chilled, and specialty dairy formats, while food-service and retail channels continue to demand dependable availability across broader geographic footprints. This has contributed to longer supply chains and greater reliance on controlled cold storage and transport for categories such as milk, cheese, yogurt, and cream-based products. At the same time, manufacturers are diversifying sourcing footprints, which increases the need for cross-border and inter-regional refrigerated movement. Growth is therefore not only about moving more volume; it is about moving a wider mix of dairy products with different temperature tolerances, shelf-life profiles, and handling requirements. Logistics providers that can manage product differentiation at scale gain a clear advantage because they can support both routine bulk movement and higher-touch specialty dairy flows within a coherent network.
Supply chain structure and cost dynamics are acting as a second-order driver, pushing organizations to optimize asset use and reduce waste. Cold storage capacity remains a strategic constraint in several regions, particularly where demand for chilled dairy inputs is rising faster than facility development. That constraint encourages investment in automated storage, higher-density layouts, and better throughput management. On the transportation side, cost variables such as reefer-specific freight rates, driver economics, and packaging input pricing all influence lane decisions. The result is a market in which efficiency is becoming inseparable from service quality. Operators are increasingly evaluated on whether they can reduce dwell time, improve load consolidation, limit temperature-related losses, and stabilize total landed cost, rather than simply offering a refrigerated slot or a warehouse location.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is anchored by large logistics and cold chain organizations with the scale to design integrated dairy networks rather than isolated refrigerated services. Maersk has positioned itself around refrigerated container shipping and cold chain solutions for dairy products including milk, cheese, and butter, leveraging global ocean connectivity and increasingly digital reefer capabilities. DB Schenker focuses on temperature-controlled logistics and multimodal transport, using specialized reefer trucks and warehousing to support dairy supply chains across complex routing scenarios. Kuehne+Nagel has built a reputation around end-to-end cold chain management, combining sea freight in reefer containers with air cargo options for perishable dairy goods, which helps shippers handle urgent or high-value movements without breaking the cold chain. DHL Supply Chain adds depth in temperature-monitored trucking, warehousing, and distribution networks spanning Europe, the Americas, and Asia, positioning itself as a multi-region execution partner for dairy operators.
In cold storage, Americold and Lineage Logistics bring different but complementary forms of scale. Americold operates one of the largest cold storage networks globally, with precise temperature control that supports dairy storage and downstream logistics. Lineage Logistics has expanded its footprint as a global leader in temperature-controlled logistics, combining warehousing, transport, and traceability for dairy supply chains. Nichirei Logistics plays a distinct role in Asia-Pacific markets, providing refrigerated transport and cold storage for dairy imports and distribution, where growing demand and import dependence create specialized regional needs.
What separates the leaders is not only asset scale, but the ability to connect physical infrastructure with technology, compliance, and service design. Recent activity reflects this orientation. Maersk expanded reefer capacity for dairy exports from Europe to Asia while adding real-time temperature monitoring, effectively pairing capacity growth with visibility. Lineage Logistics opened an automated cold storage facility in the Netherlands dedicated to dairy logistics serving EU markets, strengthening its position in a region where regulated cold chain expectations and proximity to demand matter. Kuehne+Nagel introduced a reefer platform with blockchain traceability for dairy shipments, reinforcing the move toward documentation and shipment integrity as competitive differentiators rather than optional features. These moves suggest a market in which differentiation is increasingly expressed through data assurance, automation, and regional specialization.
The broader competitive trend is one of selective consolidation alongside targeted specialization. Large players are strengthening integrated networks that span transport, storage, and monitoring, while regional specialists continue to compete on local market knowledge, import/export handling, and tailored compliance execution. At the same time, new entrants and niche operators can find room where specific product categories, lanes, or compliance requirements are underserved. The result is a landscape that is not simply consolidating into a few dominant incumbents, but one where the practical battleground is shifting toward reliability, traceability, and the ability to handle dairy’s varied temperature and packaging demands across multiple trade lanes. Market participants that can combine scale with product-level precision are best positioned to capture value, while those relying on commoditized refrigerated capacity alone face growing exposure to price and performance pressure.
Future Trends
Over the next three to five years, one of the clearest trends will be the continued elevation of cold chain visibility from a supporting function to a core commercial requirement. Dairy buyers, manufacturers, and retail partners are likely to place greater weight on temperature documentation, exception handling, and audit-ready records when selecting logistics partners. This will favor operators that can deliver consistent monitoring across transport and storage, integrate data from different legs of the journey, and translate that data into actionable service commitments. The commercial opportunity lies in turning visibility into differentiated service levels, where shippers can align product category, risk tolerance, and routing choices with measurable cold chain performance.
A second trend will be the deepening integration of automation and smarter cold storage design. As demand for chilled dairy products grows and labor economics remain tight, facilities that improve throughput, reduce handling errors, and support more consistent temperature control will gain strategic value. Automation is unlikely to replace the full breadth of cold chain work, but it can materially improve the consistency of high-volume dairy storage and dispatch, especially in regions where capacity is strained. The opportunity here is not simply building more space; it is improving how space is used, how inventory moves through it, and how product integrity is preserved during transitions between storage, transport, and distribution.
A third trend is the increasing influence of regulatory and packaging requirements on logistics operating models. Rules around temperature recording and packaging content are expanding the baseline expectations for dairy movement, and these expectations will likely become more granular over time. Logistics providers and dairy operators that proactively align their equipment, documentation, and material choices with evolving standards will face fewer disruption points, while late adapters may incur rework, delays, or renegotiation costs. The associated risk is that compliance costs and packaging transitions can compress margins if they are treated as isolated procurement issues rather than integrated logistics decisions. Climate-related disruptions, energy volatility, and geopolitical shifts in trade routes also remain external uncertainties that could pressure transit times, facility operations, and cost planning.
Actionable Guidance for Decision Makers
For dairy manufacturers and processors, the priority is to treat cold chain performance as a product-level design parameter rather than a downstream service choice. Selecting logistics partners should involve aligning temperature tolerance, shelf-life expectations, and packaging choices with the capabilities of the transport and storage network, especially for categories that move across longer distances or multiple regulatory environments. Building visibility requirements into contracts and service agreements can help reduce quality risk and improve responsiveness when deviations occur. For investors, the most durable opportunities are likely to be tied to operators that combine scale with technology-enabled reliability, automation-ready cold storage, and compliance-ready service architectures. Capital allocation should favor businesses that can demonstrate measurable improvements in temperature integrity, throughput efficiency, and documentation consistency, since these attributes are increasingly tied to competitive positioning.
For procurement and supply chain leaders, the practical focus should be on total landed cost and risk reduction rather than unit transport price alone. That means evaluating carrier and warehouse partners on performance indicators relevant to dairy: temperature excursion handling, dwell time, load consolidation, and packaging alignment with evolving content requirements. Procurement strategies that incorporate packaging durability, reuse potential, and regulatory trajectory can help reduce future disruption and cost shock. For organizations seeking a sharper segment view, detailed breakdowns by region, service type, and application can help pinpoint where to prioritize capacity, renegotiate contracts, or invest in technology and compliance readiness. A full market report with deeper segmentation, competitive benchmarks, and scenario-based insight can support more targeted planning across those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Dairy Logistics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Conveyor Buffer Beds Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Conveyor Buffer Beds Market Overview
The Conveyor Buffer Beds Market is a vital segment within material handling and automation industries, providing essential solutions for buffering, accumulating, and aligning products during manufacturing and logistics processes. These systems are designed to optimize workflow, reduce downtime, and enhance operational efficiency by controlling the flow of items along conveyor lines. Their core functionalities include adjustable buffering capacity, seamless integration with existing conveyor systems, and compatibility with various product types, supporting industries such as automotive, packaging, and electronics.
The Conveyor Buffer Beds Market plays a crucial role in modern industrial automation, enabling continuous production lines and minimizing bottlenecks. The market size and importance are driven by increasing demand for efficient supply chain solutions and advanced manufacturing technologies. The Conveyor Buffer Beds Market is expected to grow steadily, reflecting rising automation investments and technological innovations across multiple sectors.
Market Size and Growth
The current market value of the Conveyor Buffer Beds Market is estimated at approximately USD 1.2 billion. Over the next decade, it is projected to reach around USD 2.8 billion, with a compound annual growth rate (CAGR) of about 9%. Growth drivers include the expansion of automation in manufacturing, the need for flexible and scalable buffering solutions, and the adoption of Industry 4.0 practices. Increasing logistics and warehouse automation also significantly contribute to market expansion.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2192
Key Drivers
• Rising automation in manufacturing industries
• Increasing demand for flexible production lines
• Adoption of Industry 4.0 and smart factory concepts
• Growth in e-commerce and logistics sectors
• Need for efficient workflow management
Restraints
• High initial investment costs
• Technical complexity of integration
• Regulatory compliance challenges
• Limited awareness in emerging markets
• Operational maintenance expenses
Segmentation
• By Type: Fixed Buffer Beds, Adjustable Buffer Beds, Modular Buffer Beds
• By Deployment: Automated, Semi-Automated, Manual
• By Enterprise Size: Small, Medium, Large
• By End User: Automotive, Food & Beverage, Electronics, Logistics, Others
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits strong demand driven by advanced manufacturing and logistics sectors, with high adoption of automation technologies. Europe’s market growth is fueled by strict regulations and a focus on Industry 4.0, leading to increased integration of buffer systems. Asia-Pacific shows rapid expansion due to manufacturing growth, especially in China, India, and Southeast Asia, with rising investments in automation. Latin America’s market is gradually developing, supported by industrialization efforts and infrastructure projects. Middle East & Africa are emerging markets with potential driven by industrial diversification and modernization initiatives.
Opportunities
• Expansion into emerging markets with developing manufacturing bases
• Integration of IoT and smart automation technologies
• Innovation in compact and space-saving buffer bed designs
• Adoption by e-commerce and logistics hubs for faster throughput
• Customization for industry-specific applications and compliance
Key Companies
Daifuku Co., Ltd.
FlexLink Systems AB
Hytrol Conveyor Co., Inc.
Interroll Holding AG
Qimaroq Group
Vanderlande Industries
Vention Inc.
BSH Bosch und Siemens Hausgeräte GmbH
Bastian Solutions
GHM Group
Cimcorp
Conclusion
The overall outlook for the Conveyor Buffer Beds Market remains positive, with long-term growth driven by increasing automation and Industry 4.0 adoption across industries. Strategic investments in innovative buffering solutions are expected to underpin sustained expansion. As industries continue to prioritize efficiency and flexibility, the market for conveyor buffer beds will play a vital role in shaping future manufacturing and logistics landscapes.
Related Reports
Lithium Battery Ultrasonic Welding Machine Market , Size Share and Analysis | Report 2033
Power Battery Ultrasonic Welding Machine Market , Size Share and Analysis | Report 2033
Sintered Friction Pads Market , Size Share and Analysis | Report 2033
Maglev Centrifugal Chillers Market , Size Share and Analysis | Report 2033
Maglev Turbo Blowers Market , Size Share and Analysis | Report 2033
Marine Nails And Beads Market , Size Share and Analysis | Report 2033
Explosion Proof Camera Systems Market , Size Share and Analysis | Report 2033
Beer Bottling Line Market , Size Share and Analysis | Report 2033
Semiconductor Ft And Cp Equipment Market , Size Share and Analysis | Report 2033
Narcotics Analyzer Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Worldwide Perfumes Market: How 5.85% CAGR and Luxury Shifts Redefine Growth
By PW Consulting, 2026-09-18
Worldwide Perfumes Market: Strategic Trends and Commercial Opportunities
Market Overview and Core Challenges
The global perfumes market has demonstrated steady expansion, moving from an estimated valuation of USD 54.5 billion in 2023 to USD 58.5 billion in 2025. Projections indicate continued growth through the forecast period, with revenues expected to reach USD 61.92 billion in 2026 and climb toward USD 87.11 billion by 2032. This trajectory reflects a compound annual growth rate of 5.85 percent over the 2026–2032 forecast period, signaling a market that is maturing yet retaining robust growth potential. The expansion is not merely a function of population growth or rising disposable incomes; it reflects deeper structural shifts in consumer preferences, distribution channels, and product positioning.
Despite this positive momentum, the industry faces several structural challenges that will shape competitive outcomes over the next decade. First, regulatory tightening continues to reshape formulation practices and cost structures. The fragrance industry operates under an evolving framework of safety standards and ingredient restrictions that require manufacturers to continuously reformulate products. Compliance with emerging restrictions on certain fragrance ingredients and essential oils has forced brands to reformulate existing creations, introducing both cost implications and potential delays in product launches. This regulatory environment favors larger companies with dedicated compliance resources while placing pressure on smaller niche players that may lack the technical infrastructure to navigate complex ingredient regulations efficiently.
Second, the market is undergoing a significant transformation in distribution and consumer engagement models. The shift toward direct-to-consumer channels, e-commerce expansion, and experiential retail has altered how fragrances are discovered, sampled, and purchased. Travel retail, historically a high-margin channel for prestige fragrances, has experienced volatility due to geopolitical tensions and shifting travel patterns, creating revenue variability for brands that historically relied on airport and duty-free locations. Companies must now balance traditional wholesale relationships with owned digital storefronts and experiential touchpoints, requiring investment in omnichannel capabilities that many mid-tier players struggle to finance.
Third, raw material volatility and sustainability expectations are converging to create a new cost and positioning paradigm. The market for natural fragrance ingredients has been valued at USD 17.1 billion as of 2022, underscoring the sustained demand for natural and sustainable perfume formulations. However, sourcing consistent-quality botanical materials while maintaining price stability remains challenging, particularly as climate variability, land-use competition, and certification requirements add complexity to supply chains. Brands that cannot secure reliable access to preferred natural ingredients or demonstrate credible sustainability claims risk losing share to competitors who can.
These challenges are not insurmountable, but they demand strategic attention. Companies that treat regulatory compliance, channel evolution, and raw material strategy as isolated operational issues will find themselves reacting rather than leading. Those that integrate these factors into a coherent market strategy will be better positioned to capture growth while managing exposure.
AI Perfume Generator Market
Key Drivers of Market Change
Technological Innovation and Formulation Advances
Innovation in fragrance creation and delivery technologies is reshaping what perfumes can achieve and how they reach consumers. Advances in olfactory science, molecular design, and encapsulation technologies are enabling brands to develop longer-lasting scents, more nuanced fragrance profiles, and products that can be tailored to specific consumer preferences. The expansion of dedicated fragrance zones at major industry events reflects the growing emphasis on new ingredients, technologies, and scent trends, with exhibits showcasing innovations from ingredient suppliers and formulation houses. These platforms serve as critical nodes where technical breakthroughs translate into commercial opportunities, allowing brands to source differentiated scent solutions and stay ahead of consumer expectations for novelty and quality.
Beyond formulation, digital tools are transforming how fragrances are developed, tested, and marketed. Data-driven consumer insights, predictive analytics, and virtual sampling technologies are reducing the friction between product creation and market validation. Brands that invest in these capabilities can iterate more quickly, respond to emerging taste shifts, and personalize offerings at a level that was previously impractical. The integration of technology into fragrance development is not merely an operational efficiency play; it is becoming a differentiator that influences brand perception and consumer loyalty in an increasingly crowded market.
Regulatory and Compliance Landscape
The regulatory environment continues to be a defining force in the perfumes market, with implications that extend beyond compliance into product strategy and brand positioning. International fragrance associations have published updated transparency lists detailing thousands of ingredients used across the industry, providing greater visibility into the composition of fragrance products. At the same time, amendments to usage restrictions have required full compliance for existing creations within specific timelines, forcing reformulation of products containing restricted substances. These developments create both operational burdens and strategic opportunities.
For large multinational brands, regulatory change is absorbed as part of a broader compliance infrastructure, often integrated with sustainability and safety messaging that resonates with conscious consumers. For smaller brands, the cost and complexity of reformulation can be a barrier, but it can also serve as a filter that benefits those with strong technical partnerships and agile development processes. The transparency trend also aligns with broader consumer demand for ingredient clarity, suggesting that regulatory compliance and marketing communication around ingredient safety and sourcing will become increasingly intertwined in the years ahead.
Demand-Side Shifts in Consumer Behavior
Consumer behavior is evolving in ways that directly influence fragrance purchasing patterns. There is a growing appetite for personalization, self-expression, and emotional connection through scent, driving demand for products that feel distinct and meaningful rather than generic. This has fueled interest in unisex fragrances, niche and artisanal offerings, and fragrances that align with individual identity and lifestyle values. At the same time, the luxury segment continues to command a significant share of market value, reflecting the enduring appeal of prestige branding, heritage, and aspirational positioning. Luxury perfumes represent a substantial portion of overall market revenue, highlighting the importance of premium positioning even as mass-market options remain relevant for broader consumer segments.
Gender-based segmentation is also evolving. Women's fragrances continue to represent the largest consumer group, but men's fragrances and unisex options are gaining traction as traditional gender boundaries in beauty and personal care blur. This shift creates opportunities for brands to develop inclusive scent narratives and expand their addressable market. Consumers are also increasingly influenced by social media, influencer culture, and experiential marketing, making discovery and endorsement dynamics more fluid and fast-moving than in previous eras. Brands that can leverage these channels authentically while maintaining product quality and brand integrity are better positioned to capture attention and convert it into sustained purchase behavior.
Supply Chain and Cost Structure Dynamics
Supply chain pressures and cost structures are reshaping how fragrance companies manage production, sourcing, and pricing. The post-pandemic recovery brought initial normalization, but subsequent geopolitical tensions and logistical disruptions have introduced renewed variability. Travel retail slowdowns linked to regional instability have impacted sales for several major fragrance players, with estimates indicating a measurable negative effect on group sales during recent quarters. These disruptions highlight the vulnerability of channel-dependent revenue streams and the importance of diversification across geographies and distribution models.
Raw material costs remain a critical factor, particularly for brands that emphasize natural ingredients or premium botanical components. Price volatility in essential oils and other natural materials can compress margins if not managed through forward contracting, supplier diversification, and formulation flexibility. At the same time, the rising cost of compliance, packaging, and sustainability certification adds to the overall cost base. Companies that build resilient supply chains, invest in ingredient substitution strategies, and maintain transparency with consumers about sourcing and pricing are better equipped to protect margins without sacrificing brand value.
Competitive Landscape and Leading Strategies
The competitive structure of the worldwide perfumes market is characterized by a mix of large diversified beauty and luxury conglomerates, specialized fragrance houses, and ingredient suppliers that play a critical role in enabling product innovation. Market concentration data indicates that the top three companies hold approximately 28.5 percent of total market revenue, while the top five account for roughly 41.2 percent. This level of concentration suggests a market where scale, brand portfolio breadth, and distribution capabilities confer advantages, but it also leaves meaningful space for specialized players and regional leaders to compete on differentiation, agility, and niche positioning.
L'Oréal Groupe stands as a global leader in beauty with an extensive fine fragrance portfolio spanning brands such as Lancôme, Yves Saint Laurent, and Giorgio Armani perfumes. Its strength lies in the ability to operate across both mass and prestige segments worldwide, leveraging broad distribution networks, consumer data, and marketing scale. The Estée Lauder Companies Inc. maintains a major presence in prestige fragrances through brands including Estée Lauder, Tom Ford, Jo Malone London, and Le Labo, with a strong focus on luxury perfume offerings that emphasize brand heritage, craftsmanship, and premium positioning. Coty Inc. operates a large portfolio of licensed and owned fragrances, including Gucci, Calvin Klein, Marc Jacobs, and Burberry, giving it significant presence in both mass and prestige segments and enabling it to capture demand across multiple price points and consumer segments.
LVMH Moët Hennessy Louis Vuitton reinforces the luxury fragrance landscape through iconic perfume houses under Parfums Christian Dior, Givenchy, and Kenzo, with active involvement in high-end fragrance creation and distribution. Puig, a family-owned group specializing in fashion and fragrance, competes with brands such as Carolina Herrera, Paco Rabanne, Jean Paul Gaultier, and Byredo, maintaining a strong force in global perfumes through a blend of licensed and owned brands. Shiseido Company Ltd. offers premium fragrances through its own brand and subsidiaries, with active participation in Asian and international markets. Chanel S.A. remains an iconic luxury house with flagship perfumes including Chanel No. 5 and other high-end fragrance lines, benefiting from an unparalleled brand legacy and consistent demand for its prestige offerings.
Beyond brand owners, the ingredient and creation side of the market is dominated by firms that supply the fragrance industry with specialized capabilities. Givaudan operates as a leading fragrance ingredient and creation house, focusing on fine fragrance development and innovation for major brands worldwide. International Flavors & Fragrances (IFF) serves as a global supplier of fragrances and scents, creating perfumes for numerous consumer brands and holding a significant share in fine fragrance compounding. DSM-Firmenich, following its merger, has become a major player in fragrance creation, supplying luxury and mass-market perfume houses with innovative scent solutions. Symrise provides fragrances and flavor solutions to the perfume industry, with an active focus on sustainable and fine fragrance development. These suppliers are not merely cost providers; they are innovation partners whose capabilities influence product differentiation, speed to market, and sustainability outcomes.
Recent industry developments illustrate how the competitive landscape is evolving. In early 2026, Puig and The Estée Lauder Companies confirmed discussions regarding a potential business combination that could create a major luxury beauty group with a strengthened position in the global fragrance market. Such consolidation would reflect a broader trend toward scale and portfolio strength in the prestige segment, as companies seek to combine brand equity, distribution reach, and creative capabilities. At the same time, new entrants and brand extensions continue to test the market, as demonstrated by the debut of a first prestige fragrance from a fashion brand entering the high-end perfume segment, signaling that luxury fragrance remains an attractive adjacency for established names in adjacent categories.
The competitive dynamics suggest several strategic imperatives. Large players are pursuing integration and portfolio optimization to strengthen their position across segments and geographies, while also investing in innovation pipelines that keep brands relevant. Mid-tier and niche brands are competing through storytelling, ingredient differentiation, direct consumer relationships, and channel specialization. Ingredient suppliers are increasingly important strategic partners, offering not only raw materials but also formulation expertise, sustainability credentials, and speed to market. The market is likely to continue evolving through a combination of consolidation among established players, entry of new brand names from fashion and lifestyle sectors, and growing importance of supplier collaboration in driving differentiation.
Perfume Market
Future Trends and Commercial Implications
Looking ahead to the next three to five years, several trends are likely to shape the trajectory of the worldwide perfumes market and create distinct commercial opportunities. The first is the continued premiumization and personalization of fragrance offerings. As consumers seek products that reflect individual identity and emotional resonance, brands that can deliver customized or semi-customized scent experiences, supported by digital tools and data insights, will be well placed to capture higher-margin demand. This trend favors companies with strong creative capabilities, agile development processes, and direct consumer engagement channels that enable feedback loops between product development and market response.
The second trend is the deepening integration of sustainability and transparency into brand strategy and product design. Consumers and regulators alike are pushing for clearer ingredient disclosure, responsible sourcing, and credible environmental claims. Brands that can demonstrate authentic sustainability practices, whether through natural ingredient sourcing, reduced environmental footprint, or ethical supply chain management, will differentiate themselves in a market where green claims are increasingly scrutinized. This creates opportunities for ingredient suppliers and formulation houses that can provide verified sustainable solutions, as well as for brand owners that can communicate these attributes effectively without overstating their impact.
The third trend is the ongoing reconfiguration of distribution and channel strategy. E-commerce, direct-to-consumer models, and experiential retail are expected to grow in importance, while traditional wholesale and travel retail may remain subject to volatility. Brands that build flexible, omnichannel capabilities and can shift sales mix toward higher-margin owned channels will be more resilient to external shocks and better positioned to capture consumer attention across touchpoints. At the same time, companies must manage the complexity of channel conflict, inventory allocation, and brand experience consistency as they expand their digital and physical presence.
These trends carry both opportunities and risks. Premiumization and personalization can drive margin expansion, but they also require investment in technology, talent, and consumer insight capabilities that may be challenging for smaller players. Sustainability and transparency can enhance brand equity, but they demand rigorous execution and credible evidence to avoid backlash from skeptical consumers and regulators. Channel reconfiguration can improve resilience and profitability, but it introduces operational complexity and may require renegotiation of existing wholesale relationships. Companies that approach these trends with a clear strategic framework and timely access to market intelligence will be better equipped to navigate uncertainty and capture growth.
Strategic Recommendations for Decision Makers
For manufacturers and brand owners, the priority is to strengthen innovation pipelines and formulation agility while embedding sustainability and compliance into product development from the outset. Investing in partnerships with ingredient suppliers that offer both creative and technical capabilities can accelerate time to market and improve differentiation. At the same time, diversifying distribution channels and building direct consumer relationships can reduce dependence on volatile channels and create richer data for product refinement and marketing.
For investors, the market presents opportunities in companies with strong brand equity, scalable distribution, and credible sustainability positioning, as well as in suppliers that provide differentiated ingredient and formulation capabilities. Due diligence should focus on the ability to navigate regulatory change, manage raw material volatility, and execute channel transformation, rather than relying solely on historical revenue trajectories. Consolidation activity may create value through portfolio synergies, but integration risk and brand preservation should be weighed carefully.
PW Consulting
For procurement and sourcing teams, securing resilient supply chains for natural and sustainable ingredients is essential to protect both cost structures and brand promises. Diversifying suppliers, exploring alternative materials where appropriate, and establishing clear quality and compliance benchmarks can reduce exposure to volatility while supporting product positioning. Close coordination with formulation and regulatory teams will be critical to balancing cost, performance, and compliance objectives.
Timely access to detailed market intelligence remains a critical enabler for all these actions. The perfumes market is evolving rapidly across regulation, consumer behavior, channel dynamics, and competitive structure, and decisions made without current, granular data carry higher risk. For those seeking deeper segmentation data, regional breakdowns, and customized strategic guidance, PW Consulting's comprehensive research report on the worldwide perfumes market provides the detailed analysis needed to inform investment, product, and sourcing decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Perfumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Vibrating Wire Weir Monitor Market: 6.12% CAGR Signals 2032 Buy
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Vibrating Wire Weir Monitor Market
Market Overview and Core Challenges
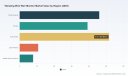
The global vibrating wire weir monitor market has demonstrated consistent growth over the past five years, with total revenue expanding from approximately USD 115.42 million in 2020 to an estimated USD 155.4 million in 2025. This trajectory reflects a compound annual growth rate of 6.12 percent through the forecast period extending to 2032, when market size is projected to reach USD 235.52 million. The measured expansion is not merely a function of incremental demand but rather a structural shift driven by aging infrastructure, heightened regulatory scrutiny, and the broader transition toward automated, data-rich monitoring systems in water management and geotechnical applications.
Despite the upward momentum, the sector operates under several persistent constraints that shape commercial strategy and investment timing. First, the market remains moderately concentrated, with the top three players accounting for roughly 38 percent of total revenue and the top five capturing just over half. This concentration indicates established competitive moats around technical validation, long-term deployment records, and relationships with dam safety and mining operators, but it also leaves room for specialized entrants who can differentiate on application-specific engineering or regional service capability. Second, the product landscape is dominated by a handful of standardized configurations, with V-notch designs representing the largest share of type-specific demand, followed by rectangular and trapezoidal variants. While this maturity reduces integration risk for end users, it also compresses differentiation opportunities for generic offerings and pushes competition toward ancillary services such as calibration, data integration, and lifecycle maintenance. Third, procurement cycles in core application areas—dam and reservoir monitoring, mining operations, landfill and industrial site management, and broader water resource programs—tend to be long, specification-driven, and heavily influenced by institutional procurement rules and engineering consultants. These dynamics create entry barriers but also reward suppliers who can align product capabilities with recognized standards and demonstrate measurable operational value over multi-year deployments.
Together, these conditions define a market that is growing steadily but rewards disciplined positioning, technical credibility, and close alignment with end-user operational priorities rather than broad-based price competition.
Key Demand Drivers and Structural Shifts
Several interconnected forces are shaping the next phase of market development, and each carries distinct implications for manufacturers, investors, and procurement teams.
Technology performance and signal integrity. Vibrating wire sensing architecture continues to anchor the segment because it offers stable, low-drift measurements over long cable runs and in environments where temperature variation, electrical noise, or remote placement would degrade alternative sensor types. Technical documentation from leading suppliers underscores that these monitors can detect small changes in water level with high resolution while maintaining long-term stability, a combination that is especially valuable in seepage monitoring and dam safety programs where data continuity is critical. The practical consequence is that engineering teams increasingly view vibrating wire weir monitors not as isolated instruments but as integral components of automated monitoring chains, where reliable signal quality reduces false alarms, lowers inspection overhead, and supports more confident decision-making.
Vibration Monitoring Equipment Market
Regulatory and standardization pressure. Dam safety instrumentation expectations in major markets emphasize durability, reliability, and compatibility with long-term automated systems, and vibrating wire sensors are frequently referenced in that context because of their performance profile in weir and piezometer applications. At the same time, V-notch weir configurations used for flow measurement in safety-critical programs are commonly specified with reference to established standards for accurate open-channel and reservoir seepage monitoring. These expectations do not merely create compliance requirements; they influence specification language, procurement preferences, and the pace at which operators replace legacy instrumentation. Suppliers that can map their product documentation, calibration practices, and installation support to recognized standards are better positioned to participate in institutional tenders and multi-year monitoring programs.
Application expansion beyond traditional hydrology. While dam and reservoir monitoring remains the largest demand pool, mining operations and landfill or industrial site management represent substantial and growing usage areas. In mining, water level and seepage monitoring intersects with operational safety, closure planning, and environmental compliance, which encourages operators to standardize on instrumentation that can be deployed across multiple sites and integrated into centralized data workflows. In landfill and industrial contexts, monitoring needs are often tied to containment integrity and regulatory reporting, where robust hardware and predictable maintenance cycles matter more than marginal cost differences. This broadening application base diversifies revenue exposure and gives suppliers additional pathways to scale without relying solely on large dam and reservoir programs.
PW Consulting
Materials, integration, and total cost of ownership. The core hardware typically relies on high-grade stainless steel for the force transducer, cylindrical weight, and housing components to maintain corrosion resistance and long-term stability in submerged or wet environments. That material emphasis is not cosmetic; it directly affects service life, calibration intervals, and replacement frequency, which in turn shape total cost of ownership for operators managing remote or hard-to-access installations. At the same time, the growing availability of automation interfaces and data acquisition options is shifting purchasing criteria from unit price toward integration capability, remote readability, and support responsiveness. In practice, this means competitive advantage increasingly depends on how well a monitor can be installed, maintained, and incorporated into existing telemetry or asset management environments, rather than on sensor performance alone.
Competitive Positioning and Landscape Evolution
The market is defined by a small group of established manufacturers that compete on technical reputation, application-specific refinement, and long deployment pedigrees. Several patterns distinguish the leading positions.
Precision, stability, and specification alignment. Companies such as GEOKON, based in Lebanon, New Hampshire, have built their positioning around precision water level monitoring systems that use vibrating wire force transducers with cylindrical weights tailored for weirs, tanks, streams, and reservoirs. The commercial strength of this approach lies in the combination of high resolution, stable long-term performance, and clearly documented measurement ranges, which helps engineering teams specify equipment with confidence in safety-critical environments. In the United Kingdom, Geosense has emphasized its VWM-2000 design as part of dam safety programs, using a vented vibrating wire force transducer and cylindrical weight to support accurate monitoring in weirs, streams, reservoirs, and tanks. That program-oriented framing reflects a broader competitive trend: suppliers are not only selling sensors, but also positioning them as components of institutional safety and compliance workflows. Soil Instruments has taken a somewhat different angle with its V-notch weir monitor, emphasizing robust, low-cost water level monitoring with cylindrical weight suspension from a force transducer and support for automation through data acquisition. This configuration appeals where durable performance and straightforward integration are prioritized over premium feature sets.
Regional specialization and application tailoring. In Australia, both HMA Group and Geomotion have focused on vibrating wire weir monitoring for geotechnical and open-channel applications. HMA Group supplies monitors commonly installed in V-notch weirs using vibrating wire force transducers for highly stable and sensitive water level monitoring in geotechnical settings, while Geomotion offers systems that combine stainless steel V-notch weir plates with vibrating wire water level sensors for precise seepage flow measurement in dams, rivers, streams, and open channels, including automation options. This regional concentration matters because local experience with site conditions, installation practices, and client expectations can become a durable advantage in markets where field reliability and after-sales support weigh heavily in purchasing decisions.
Worldwide Surface Water Measuring Instrument Market
Consolidation pressure and differentiation pathways. Because the top five participants already account for a majority of revenue, future consolidation is likely to come less from dramatic share grabs and more from targeted acquisitions, distribution partnerships, or capability expansion into adjacent monitoring segments such as piezometers, tiltmeters, or automated data platforms. At the same time, the market is not closed to new entrants who can bring genuine differentiation. Potential entry points include application-specific designs for harsh or specialized environments, stronger native integration with remote telemetry and analytics, improved calibration and service models that reduce lifecycle cost, and regional service networks that shorten response times for remote installations. Conversely, suppliers that compete primarily on price without clear evidence of performance, durability, or integration benefits face increasing pressure, especially as end users become more sophisticated about total cost of ownership and long-term data reliability.
The landscape is therefore evolving toward a dual structure: entrenched incumbents competing on proven stability, standards alignment, and institutional trust, alongside specialized players seeking advantage through integration, service, and tailored engineering.
Forward Outlook: Trends Shaping the Next Three to Five Years
Looking ahead, several trends are likely to define the market’s direction and shape commercial opportunity.
Automation and remote data integration will become default expectations rather than optional upgrades. As dam safety programs, mining operations, and industrial site monitoring increasingly rely on centralized data workflows, weir monitors that can connect cleanly to acquisition systems and support remote reading will gain preference. The commercial implication is that hardware alone will be less differentiated; suppliers will need to demonstrate installation simplicity, signal compatibility, and support for ongoing data management.
Demand will continue to broaden across application verticals, with mining and containment monitoring gaining relative importance. Even though dam and reservoir programs remain the largest single demand pool, growth in mining and landfill or industrial site use cases adds diversification and creates opportunities for suppliers that can adapt configurations to different site constraints and reporting requirements. This spread also reduces dependence on any single procurement pipeline, which can soften cyclical risk for manufacturers with balanced portfolios.
Standards-aligned specification language will increasingly gate market access. Where procurement teams and engineering consultants reference recognized standards for flow measurement and instrumentation durability, products that can clearly document conformance and long-term performance will enjoy an advantage in bidding and specification processes. Over time, this favors suppliers that invest in documentation, testing, and service transparency, and it raises the stakes for newcomers who must prove credibility quickly.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of steady market growth, expanding application use, and rising expectations for automation creates space for companies that can deliver reliable hardware with strong integration and service support. On the risk side, long procurement cycles, concentrated incumbency, and sensitivity to material and installation costs mean that entry timing, regional coverage, and lifecycle economics matter as much as product performance. Macroeconomic pressure on infrastructure spending, changes in dam safety funding, or shifts in mining capital expenditure could slow demand in specific regions or segments, even as the broader trajectory remains positive.
Strategic Implications for Decision Makers
For manufacturers, the priority is to reinforce differentiation beyond base sensor performance. That means investing in automation-friendly interfaces, clear standards-aligned documentation, and service models that reduce total cost of ownership over the installation life. Suppliers that can show measurable reliability in remote or corrosive environments, and that can support calibration and data integration without heavy customization, are better positioned to defend margin and win specification-driven bids.
For investors, the most relevant signal is that moderate concentration and steady growth do not automatically translate into easy expansion. Value creation is likely to come from targeted capability builds—regional service strength, integration with monitoring platforms, or product extensions into adjacent geotechnical instrumentation—rather than from undifferentiated scale alone. Due diligence should focus on deployment track records, specification win rates, and the extent to which a company’s offering is tied to long-term institutional programs versus shorter, price-sensitive purchases.
For procurement and engineering teams, the practical lesson is to evaluate weir monitors as part of a longer lifecycle equation. Signal stability, compatibility with existing data acquisition, corrosion-resistant construction, and supplier support responsiveness should carry as much weight as initial purchase price, especially in remote or safety-critical deployments where downtime and re-installation costs can quickly outweigh hardware savings.
Detailed segmentation data, company-level positioning, and application-specific demand profiles can sharpen these decisions further. The full PW Consulting market study provides deeper breakdowns and customized strategic guidance for organizations that need to translate these macro trends into operational choices.
For detailed analysis of this topic, please visit the official page: Worldwide Vibrating Wire Weir Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Roasted Pyrite Market 2026: Why 3.86% CAGR and Asia Pacific Growth Signal Repricing
By PW Consulting, 2026-09-18
Roasted Pyrite Market: Strategic Trends and Commercial Opportunities (2025–2032)
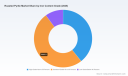
The roasted pyrite market has entered a phase of measured expansion, shaped by steady demand from heavy industry and evolving processing standards. Over the past five years, the sector has grown from a base of roughly 402 million USD in 2020 to an estimated 486 million USD in 2025. Looking ahead, the market is projected to reach approximately 633 million USD by 2032, translating to a compound annual growth rate of 3.86 percent across the forecast window. This trajectory reflects a maturing commodity market where volume growth is increasingly tied to efficiency gains, regulatory compliance, and shifting end-use priorities rather than raw demand expansion alone.
For decision-makers evaluating exposure to roasted pyrite, the headline numbers mask a more nuanced reality. Growth is neither uniform nor automatic. The market is navigating a series of structural pressures that will determine which participants capture value and which face margin compression. Understanding these pressures is essential for shaping procurement strategies, capital allocation, and long-term positioning.
Sulphur Bentonite Market
Current Market Profile
The market's footprint is heavily concentrated in a few key application streams, with steel and iron production accounting for the largest share of consumed roasted pyrite, followed by cement manufacturing, paint and pigments, and glass and ceramics. This distribution underscores the material's role as both a chemical input and a functional additive across foundational industrial sectors. Regionally, Asia Pacific dominates consumption, reflecting the scale of metallurgical and cement operations in the area, while Europe, North America, the Middle East and Africa, and Latin America collectively represent more diversified but smaller demand pools. The market structure remains moderately consolidated, with the top three participants holding roughly 42.5 percent of overall share and the top five accounting for 58.3 percent. Such concentration suggests that scale, processing capability, and supply reliability continue to differentiate leading suppliers from smaller or more regionally focused players.
Core Challenges and Inflection Points
Despite the outward growth trajectory, the industry faces several interlocking challenges that will define competitiveness over the next cycle.
Sulphur Recovery Market
- Cost volatility and margin sensitivity. Raw material pricing for pyrite and related sulfur-bearing minerals has shown notable swings, with export benchmarks for roasted iron pyrites from key origins rising sharply in periods of tight supply. For downstream buyers, particularly in sulfur-dependent processes, these fluctuations translate directly into cost unpredictability and pressure on procurement planning.
- Quality standardization and impurity management. As end-use applications demand more consistent performance, the tolerance for variable iron content and residual sulfur has narrowed. Lower-grade material remains commercially relevant in certain segments, but high-purity requirements in specialized applications are pushing producers and buyers alike toward tighter specification control and more advanced beneficiation.
- Regulatory and environmental scrutiny. Roasting processes inherently involve emissions control, heat recovery, and residue management. Continued operational legitimacy depends on demonstrable efficiency in sulfur capture, energy recovery, and cinder utilization. Facilities that cannot meet evolving expectations around residual sulfur levels and process cleanliness face both compliance risk and reputational exposure.
These challenges are not merely operational inconveniences; they are reshaping the logic of market participation. Companies that treat roasted pyrite as a commoditized bulk input may find themselves exposed to price swings and specification gaps, while those that align sourcing and processing with quality, compliance, and reliability are better positioned to secure long-term contracts and steadier margins.
Key Drivers Shaping the Roasted Pyrite Market
The market's trajectory is being pulled forward by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver reinforces the others, creating a environment where efficiency, consistency, and supply security carry disproportionate strategic weight.
Technology Innovation and Processing Breakthroughs
Advances in roasting technology are transforming how pyrite is converted into usable industrial materials. Fluid bed roasters capable of high throughput have become a reference point for producers seeking to balance capacity with heat recovery and sulfur capture. Alongside these established systems, flash roasting approaches are drawing attention for their ability to reduce residual sulfur in cinder to very low levels, supporting cleaner downstream acid production and more versatile cinder utilization. Such improvements matter because they directly affect both economics and environmental performance. Lower residual sulfur means less reprocessing, higher product acceptability, and reduced waste handling costs. For buyers, access to roasted pyrite produced through advanced methods can translate into more predictable yields and fewer processing interruptions.
At the product level, recent launches of higher-purity roasted pyrite concentrates illustrate how processing refinements are opening new application pathways. By lowering impurity levels and improving processing efficiency, these grades enable sulfuric acid producers and other users to operate with greater consistency and less downtime. The broader implication is that technology is not only expanding what can be produced but also raising the performance bar that market participants must meet to remain competitive.
Policy and Regulatory Environment
Regulatory dynamics continue to shape the operating context for roasted pyrite. Environmental expectations around emissions, energy recovery, and residue management are becoming more entrenched rather than receding. This is particularly relevant for sulfuric acid-related applications, where roasting remains a niche but active pathway supported by heat recovery systems and low-residual-sulfur cinder outputs. In practical terms, regulatory pressure is acting as both a constraint and a filter: it raises the cost of noncompliant operations while rewarding producers who can demonstrate credible efficiency and environmental controls.
Trade and export patterns also reflect the influence of policy and market structure. Leading export flows of roasted iron pyrites have come from a relatively concentrated set of origins, indicating that trade access, shipping logistics, and origin-specific quality reputations play a meaningful role in how supply reaches end markets. For importers and downstream manufacturers, this means supply diversification strategies must account not only for price but also for origin reliability, quality consistency, and the regulatory posture of source regions.
Demand-Side Shifts in End-Use Industries
Demand for roasted pyrite is closely tied to the operating rhythms of steel, cement, and specialty chemical sectors. In steel and iron production, the material's role as a sulfur and iron source keeps it embedded in core metallurgical workflows. Cement manufacturing represents another significant demand pillar, where pyrite derivatives contribute to process chemistry and product characteristics. Meanwhile, more specialized applications in paints, pigments, glass, and ceramics provide additional demand threads, often with higher specification requirements.
What is changing on the demand side is not necessarily the volume of material consumed in every segment, but the emphasis on quality and predictability. As industrial operators face tighter operating margins and more complex compliance obligations, they increasingly prefer supplied materials that reduce variability in downstream processing. This shift favors suppliers that can offer consistent grades, transparent quality data, and reliable delivery rather than those competing solely on lowest headline price. It also encourages end users to lock in longer-term arrangements with trusted sources, particularly where feedstock security is linked to production continuity.
Supply Chain and Cost Structure Dynamics
The cost structure of roasted pyrite is influenced by a chain of factors that extend from mining and beneficiation through roasting, logistics, and export. Recent periods have shown how quickly raw material economics can shift, with sulfur and pyrite input costs feeding into higher acid price levels in major consumer regions. In one major Asian market, average prices for concentrated sulfuric acid reached elevated levels during the year, reflecting both input cost pressure and regional supply dynamics. Such movements highlight how sensitive downstream industries are to upstream cost changes and why procurement teams monitor pyrite pricing trends as part of broader input cost management.
Supply chain resilience is becoming a strategic priority in its own right. Major restructuring activity, including acquisitions designed to secure roasted pyrite feedstock and expand downstream roasting capacity, signals that market participants are treating feedstock access as a critical asset. Partnerships focused on co-developing roasting capacity and sulfuric acid production further illustrate the trend toward integrated arrangements that reduce exposure to spot-market volatility. At the same time, new plant startups processing pyrite by-products from mining operations demonstrate how feedstock availability can be reshaped by broader mining and metals activity, creating both opportunities and dependencies for roasted pyrite supply.
Competitive Landscape and Leading Strategies
The competitive environment in the roasted pyrite market is defined by a mix of established multinational players, specialized industrial mineral suppliers, and regionally concentrated producers. Rather than competing purely on volume, leading companies are increasingly differentiating through processing capability, application know-how, and supply reliability.
Strategic Positioning of Key Players
Several companies illustrate distinct competitive approaches within the market.
- Equipment and process technology providers. Metso has built a reputation around pyrite roasting plant technology, with offerings that span sulfuric acid production, heat recovery, and metals recovery from roasted material. Its emphasis on high-capacity fluid bed roasters points to a strategy centered on enabling producers to scale efficiently while capturing energy and sulfur value. In a market where processing quality and recovery efficiency are increasingly important, technology-enabled positioning can create stickiness with customers seeking to upgrade or expand capacity.
- Industrial mineral processors and distributors. Washington Mills and Hickman, Williams & Company represent players with strong ties to industrial applications such as abrasives, metallurgy, foundry, and chemical sectors. Their relevance lies in the ability to position roasted pyrite within broader material supply chains, linking product quality to end-use performance. By serving multiple industrial segments, these companies can balance demand variability across applications and maintain relevance even when one sector softens.
- Regional producers with integrated reach. Veneta Mineraria and Chinese manufacturers such as Foshan Pyrite Mineral Materials, Tongling Weight Mineral Products, and UrbanMines reflect the importance of regional production bases with varying degrees of processing depth. UrbanMines, for example, emphasizes high-purity pyrite products delivered in roasted or calcined forms for applications including resulfurization, abrasives, and wastewater treatment. Such positioning shows how product specification and application breadth can serve as differentiation tools in a market where grade consistency and purity are increasingly valued.
Market Consolidation and Evolving Dynamics
The market's moderate concentration suggests room for both consolidation and specialization. Recent corporate activity underscores this direction. A major acquisition valued at approximately 320 million USD brought together a large group and a minerals entity to secure roasted pyrite feedstock and expand downstream roasting capacity. This type of move signals a strategic intent to control more of the value chain, reduce feedstock uncertainty, and strengthen supply credibility with downstream customers.
Partnerships are also reshaping competitive dynamics. A strategic cooperation between a leading tin company and a regional engineering partner to co-develop roasted pyrite roasting capacity and sulfuric acid production highlights how feedstock, processing, and acid output can be aligned to create mutually reinforcing assets. Similarly, the startup of a new pyrite-based plant in Indonesia, processing pyrite ore from a copper mining by-product stream to produce substantial volumes of sulfuric acid, illustrates how by-product utilization can unlock new supply and add scale to the broader ecosystem.
Taken together, these developments point to a market where competitive advantage is increasingly tied to integration, feedstock security, and process quality. New entrants and expanding regional producers can still find space, particularly where they bring specialized grades, reliable logistics, or cost-effective processing. However, long-term positioning will likely favor organizations that can combine supply reliability with verifiable quality and applicable technical support.
Forward Outlook: Trends for the Next Three to Five Years
Based on current market structure and recent developments, several trends are likely to shape the roasted pyrite market through the early part of the next decade.
Trend 1: Purity and Specification Upgrading as a Competitive Baseline
As downstream users seek to reduce variability and improve process efficiency, higher-purity roasted pyrite grades are expected to gain incremental importance, especially in applications where impurity control affects yield, emissions, or product quality. This does not mean lower-grade material will disappear; it will continue to serve cost-sensitive segments. However, the strategic center of gravity is shifting toward grades that offer predictable performance and lower residual sulfur. Companies that can reliably supply such grades, supported by consistent processing and testing, are well placed to capture premium positioning and longer-term contracts.
PW Consulting Chemical & Energy Research Center
Trend 2: Feedstock Security Driving Integration and Partnerships
The combination of raw material cost volatility and the strategic importance of continuous downstream operations is likely to sustain interest in feedstock security. Acquisitions, partnerships, and by-product utilization projects are natural responses to this pressure. Over the next several years, more market participants may pursue integrated arrangements that link sourcing, roasting capacity, and downstream output such as sulfuric acid or specialty iron-rich intermediates. For buyers, this trend could improve supply reliability in some channels while also concentrating supply access among better-integrated players.
Trend 3: Environmental Efficiency as a Commercial Requirement
Roasting technologies that improve heat recovery, reduce residual sulfur, and support cleaner cinder utilization are likely to become more central to commercial discourse. Environmental performance is increasingly intertwined with operational economics, since efficient sulfur capture and energy recovery can lower effective processing costs and improve product acceptability. Firms that invest in demonstrable efficiency gains will be better positioned to meet regulatory expectations and customer preferences, while those that lag may face both cost and market access disadvantages.
Risks and Uncertainties
These trends are not guaranteed paths. Raw material price swings can disrupt procurement plans and compress margins, particularly for buyers with limited flexibility. Regulatory shifts in key regions could alter the cost of compliance or change the attractiveness of certain roasting pathways. Demand conditions in steel, cement, and chemical sectors can also shift with macroeconomic cycles, construction activity, and metals markets. In addition, trade dynamics and export concentration mean that supply disruptions in a few origins can have outsized effects on certain import markets. Anticipating these risks requires active monitoring rather than static assumptions.
Strategic Implications and Actions for Decision-Makers
For executives, planners, and investors weighing exposure to roasted pyrite, the market's evolution suggests several practical priorities.
For Manufacturers and Industrial Buyers
Prioritize specification consistency and supply reliability over short-term price minimization. Where possible, align procurement with suppliers that can demonstrate controlled processing, clear quality parameters, and reliable delivery. Consider longer-term arrangements with credible sources to reduce exposure to spot volatility, especially if roasted pyrite is a critical input to continuous processes. Evaluate how advances in roasting technology and higher-purity grades could improve your own downstream efficiency, and factor those benefits into sourcing decisions.
For Investors and Capital Allocators
Focus on value chain positioning and feedstock security. Companies that combine reliable sourcing with scalable, efficient roasting capacity and clear downstream offtake pathways are more likely to sustain value through cycles. Pay attention to integration signals, such as acquisitions and partnerships that strengthen feedstock control or expand acid and specialty product output. Also assess regional exposure carefully, since demand concentration and export patterns can influence both growth potential and vulnerability to trade or regulatory changes.
For Procurement and Strategy Teams
Build a more dynamic view of the supply base. Track not only pricing but also origin reliability, quality trends, technology upgrades, and corporate activity that may reshape supply access. Develop contingency options for feedstock disruption, including alternative origins and specification adjustments where feasible. In a market where moderate consolidation and integrated moves are becoming more common, early awareness of structural changes can improve negotiating position and reduce surprise.
The roasted pyrite market is moving toward a landscape where quality, efficiency, and supply security matter as much as volume. For organizations that need a sharper view of segment-level dynamics, regional supply patterns, pricing context, and company-specific positioning, the full research report provides deeper segmentation data and tailored analysis to support more precise planning and timing decisions.
For detailed analysis of this topic, please visit the official page: Roasted Pyrite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
WaaS Market 2026-2032: Why 15% CAGR Signals a $75B Workspace Revolution
By PW Consulting, 2026-09-18
The Workspace as a Service Market: Strategic Trends and Commercial Opportunities (2026–2032)
Market Snapshot and Core Challenges
The Workspace as a Service (WaaS) market has transitioned from a niche remote-work solution to a foundational layer of enterprise digital infrastructure. Valued at approximately two hundred eighty-five billion dollars in two thousand twenty-five, the market has expanded at a compound annual growth rate of ten percent over the historical period, and is projected to sustain a fifteen percent CAGR through two thousand thirty-two. By the end of the forecast period, global revenue is expected to approach seventy-six billion dollars. This acceleration reflects a structural shift in how organizations provision, secure, and manage digital work environments, moving from capital-intensive on-premises desktop virtualization to subscription-based, cloud-native workspace delivery.
The current market landscape is defined by three interconnected challenges that will shape strategic decisions over the next several years. First, infrastructure costs are rising sharply as data center energy consumption scales. Data centers consumed roughly four point four percent of U.S. electrical power in two thousand twenty-three, and projections suggest this could reach as much as twelve percent by two thousand twenty-eight. Electricity typically represents twenty to thirty percent of total data center operating costs, and wholesale electricity prices in regions with concentrated data center activity have risen as much as two hundred sixty-seven percent over a five-year window in some U.S. markets. These dynamics directly compress margins for cloud-based workspace providers and force reevaluation of deployment models, particularly for latency-sensitive or compliance-heavy workloads.
Second, regulatory fragmentation around data sovereignty and vendor lock-in is reshaping procurement and architecture choices. Requirements driven by GDPR, Schrems II, and national frameworks such as Germany's BDSG and France's CNIL compel workspace providers to offer infrastructure-neutral or sovereign deployment options that mitigate exposure to extraterritorial laws like the U.S. CLOUD Act. At the same time, EU regulations including the Data Act promote data portability and fair access to non-personal data, reducing switching costs for enterprise buyers. This regulatory tailwind favors multi-cloud and interoperable workspace architectures, while penalizing proprietary, single-vendor ecosystems that cannot guarantee data locality or portable entitlements.
Third, the market is navigating a concentration-risk paradox. A relatively small group of hyperscale and platform players holds a meaningful share of revenue, creating efficiency and scale advantages but also concentrating pricing power and feature roadmaps. For enterprise buyers, this raises questions about long-term dependency and continuity. For smaller and mid-sized providers, it raises the bar for differentiation beyond core virtualization. The result is a market in which incumbents are deepening platform integration and channel reach, while challengers are pursuing vertical specialization, managed service bundling, and sovereign or regional deployment models. Each of these forces creates distinct strategic dilemmas for operators, investors, and enterprise procurement teams.
Key Drivers of Market Growth
Technology innovation remains the most visible driver, particularly the convergence of virtual desktop infrastructure with AI-ready compute and integrated identity and security stacks. Cloud providers are investing heavily in regional data center capacity to support higher-performance workspace experiences and to localize processing for latency-sensitive applications. For example, Amazon Web Services announced a ten billion dollar investment in North Carolina data centers in mid-two thousand twenty-five to expand AI infrastructure supporting workspace capabilities. This kind of capacity expansion does more than add compute; it enables denser, more responsive virtual workspaces, supports AI-assisted productivity tools within the workspace layer, and improves the economics of serving large enterprise fleets with consistent performance. At the same time, workspace platforms are increasingly bundling identity, endpoint management, and threat protection into the delivery model, reducing the operational burden on IT teams and making the workspace itself a control plane for secure access.
Policy and regulatory dynamics are acting as both a constraint and an accelerant. Data sovereignty mandates are pushing providers to offer deployment flexibility, including sovereign cloud options and regionally isolated management planes. This is not merely a compliance exercise; it is becoming a competitive differentiator for providers that can guarantee data residency while still delivering the scalability of cloud-delivered workspaces. Simultaneously, the EU's emphasis on data portability and reduced vendor lock-in is encouraging enterprises to standardize on interoperable workspace components rather than single proprietary stacks. This favors providers that articulate clear migration paths, portable entitlements, and open management interfaces. Regulatory clarity, where it emerges, tends to reward providers that have already invested in compliance-ready architecture and transparent data handling practices.
Demand-side behavior continues to evolve as hybrid work becomes a permanent operating model rather than a temporary response. Enterprises are consolidating disparate remote-access tools into unified workspace experiences that combine virtual desktops, application delivery, collaboration, and secure access under a single subscription. This consolidation reduces fragmentation, simplifies licensing, and improves user experience consistency across distributed workforces. For small and medium enterprises, managed workspace offerings reduce the need for specialized in-house expertise, turning desktop and application delivery into an operational expense with predictable scaling. For large enterprises, the value proposition shifts toward governance, compliance, and integration with existing identity and security investments, enabling them to extend consistent workspaces to contractors, acquired entities, and edge locations without rebuilding infrastructure.
Cost structure and supply chain dynamics are also reshaping the market. The rise of electricity costs and grid constraints is forcing providers to optimize workload placement, improve utilization, and in some cases shift certain workloads to lower-cost regions or cold-storage-adjacent architectures where appropriate. Hardware vendors are responding with infrastructure-as-a-service models and managed offerings that bundle devices, financing, and cloud services, giving enterprises flexible workspace ownership models. Managed service providers are expanding their role from remote administration to full lifecycle management, including onboarding, performance tuning, and compliance reporting. These supply-side shifts are lowering the effective barrier to adopting workspace services for organizations that prefer outcome-based contracts over capital procurement, while also creating new partnership opportunities between cloud platforms, hardware suppliers, and regional service providers.
Worldwide WiFi as a Service Market
Competitive Landscape and Leading Strategies
The competitive field is dominated by hyperscale platforms and established virtualization vendors, each pursuing a distinct strategic position. Amazon Web Services positions its workspace offerings as fully managed desktop virtualization with persistent virtual desktops in the cloud, emphasizing secure remote access and integration with virtual applications. Its strategic advantage lies in the breadth of the underlying cloud ecosystem, which allows workspace delivery to be tightly coupled with broader infrastructure, analytics, and AI capabilities. Microsoft anchors its position through cloud-based PC and virtual desktop infrastructure solutions that combine identity, security, and productivity tools, targeting organizations already invested in its productivity and identity ecosystems. This integration creates a strong retention dynamic for enterprises seeking a unified experience across devices and locations.
Cloud Software Group, formerly associated with Citrix, continues to compete on high-definition user experience and deep virtualization expertise, particularly through managed workspace environments that integrate with major cloud platforms. Its recent move to bring its desktop-as-a-service offering to Amazon WorkSpaces Core illustrates a strategy of portable virtualization that can ride multiple cloud backbones rather than being locked to a single provider. The eight-year strategic partnership with Microsoft, valued at 1.65 billion dollars, signals a dual play: deepening integration with Azure and Windows 365 while preserving cross-platform flexibility. Omnissa, following its spin-out, is focused on unified endpoint management and virtual desktop infrastructure for enterprise digital workspaces, and has launched a three-tier partner program to accelerate channel growth and adoption of its workspace and virtualization offerings. This channel-centric approach is designed to scale distribution while maintaining enterprise-grade feature depth.
Beyond the core platform players, a second tier of participants is shaping the market through specialization and service bundling. Google LLC offers cloud-based workstation capabilities integrated with its productivity suite, positioning for organizations that value tight collaboration integration and scalable virtual environments. Dell Technologies supplies hardware infrastructure and flexible consumption solutions that support workspace deployments, often in partnership with virtualization providers to deliver end-to-end experiences. Unisys and Evolve IP focus on managed workspace and cloud communications services for enterprise and small-to-medium clients, emphasizing secure, enterprise-grade environments and managed operations. Colt Technology Services Group contributes network and cloud connectivity services, including unified communications expansions that support secure workspace delivery, while Tech Mahindra delivers integrated digital workplace solutions for secure remote working. Econocom Group combines device management, financing, and cloud services into flexible workspace models, appealing to organizations that want to align capital planning with workspace adoption.
The market is evolving along two simultaneous axes: consolidation among platform providers seeking deeper integration and lock-in-resistant architectures, and fragmentation among specialists serving vertical, regional, or compliance-specific needs. Partnerships are becoming a primary vehicle for expansion, with vendors pairing virtualization depth with cloud scale, network reliability, or managed service reach. New entrants are most likely to succeed by targeting underserved niches—sovereign deployment, industry-specific compliance, or turnkey managed experiences for mid-market buyers—rather than challenging hyperscale platforms head-on. For enterprises, the practical implication is that procurement strategies should weigh not only feature parity but also deployment flexibility, partner ecosystem strength, and the vendor's ability to honor data locality and portability commitments over the contract lifecycle.
Forward-Looking Trends and Opportunities (2026–2030)
One clear trend is the shift toward AI-augmented workspace experiences that extend beyond remote access to include intelligent provisioning, contextual assistance, and automated performance optimization. As compute and inference capacity expands in regional data centers, workspace platforms can offer more responsive experiences and embed productivity features that reduce friction for distributed teams. The commercial opportunity lies in differentiating through workflow integration and operational efficiency rather than raw virtualization capability alone. Providers that can tie workspace performance to measurable productivity, security, and compliance outcomes will be better positioned to justify premium pricing and expansion within existing accounts.
A second trend is the rise of sovereignty-first and interoperable deployment models as regulatory expectations harden. Enterprises will increasingly require workspace architectures that can anchor data and management in specific jurisdictions while still leveraging global scale for burst capacity or disaster recovery. This creates opportunity for providers that offer transparent data handling, portable entitlements, and clear migration paths across clouds. It also raises the stakes for vendors that depend on proprietary control planes without regional isolation options, as procurement teams factor sovereignty and portability into total cost of ownership calculations.
PW Consulting
A third trend is the recalibration of operating economics as energy and grid costs influence infrastructure planning. Workspace providers and enterprise buyers alike will need to optimize workload placement, utilization, and lifecycle management to contain operating expenses. This favors flexible consumption models, managed services that improve utilization through multi-tenant efficiency, and partnership models that align infrastructure investment with actual usage patterns. The risk is that regions with constrained grid capacity or volatile electricity pricing could see higher delivery costs or capacity limits, potentially affecting latency-sensitive deployments and long-term expansion plans. Organizations that build scenario planning into their workspace strategy—comparing centralized, regional, and hybrid delivery models under different energy and regulatory assumptions—will be better prepared to manage cost and continuity risk.
Actionable Guidance for Decision Makers
For enterprise procurement and IT leaders, the priority is to align workspace strategy with data sovereignty, integration, and operating cost realities rather than treating virtual desktops as a purely tactical remote-access fix. Evaluate deployment flexibility, portability of entitlements, and the provider's ability to meet regional compliance requirements, and structure contracts to preserve multi-cloud optionality where feasible. For investors, focus on providers that demonstrate clear differentiation through managed service depth, channel partnerships, or sovereign and vertical specialization, and scrutinize operational cost exposure to energy and grid constraints as a factor in margin sustainability. For hardware and service providers, the opportunity lies in bundling infrastructure, financing, and managed operations into flexible consumption models that reduce adoption friction for mid-market and enterprise buyers, while building interoperability with major workspace platforms to avoid single-vendor dependency.
Given the pace of capacity expansion, regulatory evolution, and energy-cost dynamics, decisions made today will have multi-year implications for cost, compliance, and user experience. Organizations that need detailed segmentation data, regional deployment scenarios, and customized strategic recommendations should consult the full PW Consulting market study to pressure-test assumptions and prioritize investments with the highest strategic return.
Mobility as a Service (MaaS) Market
For detailed analysis of this topic, please visit the official page: Worldwide Workspace as a Service (WaaS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Vanadium Slag Market: Why 7.52% CAGR Redefines Steel & Energy Storage
By PW Consulting, 2026-09-18
Strategic Trends and Commercial Opportunities in the Global Vanadium Slag Market
Market Landscape and Core Challenges
The worldwide vanadium slag market has demonstrated consistent expansion over the past half-decade, with revenue scaling from approximately $684 million in 2020 to over $1,011 million in 2025. This trajectory reflects a compound annual growth rate of roughly 7.5 percent across the period, positioning the segment at approximately $1,030 million in the current base year and projecting further growth toward $1,681 million by 2032. The market's expansion is fundamentally anchored in its role as the dominant feedstock for global vanadium production, accounting for more than seventy percent of supply. Co-production models in major steelmaking hubs, particularly those processing vanadium-bearing titanomagnetite ores, have continuously augmented feedstock availability. As downstream demand diversifies beyond traditional metallurgy, the slag segment has gained renewed strategic importance, functioning both as a cost-efficient raw material pipeline and as a byproduct stream increasingly subject to targeted recovery and value-addition initiatives.
Despite the favorable growth momentum, the industry operates at a critical inflection point shaped by several structural challenges. The first revolves around feedstock concentration and geographic dependency. A disproportionate share of vanadium slag generation is tied to titanomagnetite processing in specific metallurgical corridors, making supply vulnerable to localized policy shifts, environmental restrictions, or operational disruptions at integrated steel plants. The second challenge stems from evolving regulatory frameworks that are actively reshaping material flows. Import restrictions enacted in major producing jurisdictions have redirected domestic processing toward locally generated slag, compelling producers to optimize domestic recovery infrastructure rather than relying on cross-border feedstock arbitrage. The third challenge involves cost and efficiency pressures. Traditional slag recovery routes face margin compression as energy costs fluctuate, processing complexity rises with lower-grade residues, and environmental compliance requirements tighten. Producers that fail to upgrade separation technologies, integrate circular recovery systems, or secure reliable downstream offtake agreements risk being squeezed between volatile primary vanadium pricing and increasingly stringent operational standards.
These challenges are not purely headwinds; they are actively restructuring how value is captured across the value chain. Companies that treat slag as a low-priority byproduct are finding their cost structures and supply reliability tested, while those that integrate advanced recovery, secure offtake channels, and align processing capabilities with end-market specifications are converting a traditional waste stream into a strategically positioned revenue line. The market's next phase will likely reward operators that can navigate regulatory divergence, optimize material recovery, and synchronize production planning with downstream demand cycles.
Key Drivers Shaping Market Dynamics
Technological innovation in slag processing has become a decisive competitive lever. Advanced physical separation, hydrometallurgical leaching, and integrated zero-waste system trials have materially improved recovery efficiency while reducing tailings volume. Industry pilots have demonstrated recovery rate improvements of approximately eighteen percent when modernized separation sequences are applied to vanadium-bearing residues, directly lowering unit processing costs and expanding the economically viable portion of lower-grade streams. These technical gains are shifting the economics of slag utilization, enabling producers to profitably extract value from materials that previously carried high disposal burdens. The trend is especially relevant given that vanadium pentoxide pricing in recent periods has reflected supply dynamics rooted in slag-derived recovery, making process efficiency a direct determinant of margin resilience.
Vanadium Redox Battery (VRB) Market
Policy and regulatory divergence is simultaneously reshaping feedstock routing and investment priorities. Import restrictions on vanadium slag in major producing markets have accelerated the localization of processing capacity, forcing domestic steel and vanadium operators to treat slag recovery as an in-house strategic priority rather than a tradable commodity play. At the same time, tariff adjustments on related vanadium products and by-product materials into key consuming markets have altered cross-border flow patterns, nudging producers to reconsider destination markets, offtake structuring, and regional processing footprints. These regulatory shifts are not static; they create both constraints and opportunities for operators that can align their material flows with evolving compliance requirements while maintaining supply flexibility for downstream customers.
Demand-side behavior is expanding beyond traditional steel and alloy applications. While metallurgical consumption remains the dominant demand pool, energy storage systems and chemical catalyst production are increasingly drawing on vanadium derivatives that trace back to high-efficiency slag recovery. The broadening application base introduces new specification requirements, delivery reliability expectations, and quality consistency demands that directly influence how slag is processed, refined, and commercialized. Buyers in storage and catalyst segments are progressively prioritizing supply continuity and traceability, which incentivizes producers to invest in controlled recovery pathways and cleaner output streams rather than relying on ad hoc residual collection.
Worldwide Vanadium Pentoxide for Electrolyte of Vanadium Battery Market
Cost structure evolution is reinforcing the strategic value of integrated sourcing. Because vanadium slag is largely a co-product of steelmaking operations using titanomagnetite ores, its economics are interlocked with steel production cycles, ore grade variability, and downstream ferrovanadium or chemical conversion capacity. Producers that can synchronize slag handling with steel mill throughput, optimize residue blending, and secure downstream conversion capacity are able to buffer against raw material price volatility more effectively than standalone processors. Recent operational disclosures illustrate this dynamic: producers continue to report V2O5 equivalent outputs tied to ore and residue handling, while offtake arrangements increasingly cover high-grade slag streams linked to dedicated processing facilities. Such structures reduce market risk for both sellers and buyers, stabilizing cash flows and enabling more deliberate capacity expansion decisions.
Taken together, these drivers point to a market where value creation is shifting from volume alone toward processing sophistication, regulatory alignment, and demand diversification. Operators that invest in recovery efficiency, align with localized feedstock policies, and build credible bridges to emerging application segments are positioned to capture a larger share of the value embedded in each tonne of slag.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by concentrated leadership alongside a broad base of region-specific producers, with the top three players accounting for roughly fifty-eight percent of market share and the top five approaching seventy-two percent. This concentration reflects the capital intensity of integrated slag processing, the importance of securing reliable titanomagnetite-linked feedstock, and the advantage of coordinating steelmaking operations with vanadium recovery. At the same time, the market is not monolithic; geographic positioning, processing philosophy, and downstream integration strategies create meaningful differentiation among leading operators.
Leading Chinese producers, including major groups operating in vanadium-titanium magnetite regions, derive strategic advantage from large-scale co-production within established steel complexes. Their differentiation lies in feedstock availability, integrated operations, and the capacity to treat slag recovery as a routine part of the production cycle rather than a separate commercial venture. This model supports consistent supply volumes and provides a natural hedge against slag market volatility, since slag generation is tied to ongoing steel output. Some of these operators are also advancing zero-waste system approaches, improving recovery rates while reducing environmental liabilities, which strengthens their positioning with regulators and downstream customers seeking more sustainable sourcing options.
PW Consulting
Outside China, significant producers rely on integrated mining, processing, and downstream ferrovanadium or chemical conversion capabilities. A prominent Russian steel and ferrovanadium operator illustrates the value of linking ore processing with vanadium product conversion, enabling more direct control over grade consistency and downstream specification alignment. In the Americas, specialized processors have carved out positions by focusing on residues, ashes, and slag streams for ferrovanadium and high-purity chemical production, with particular strength in spent catalyst recycling that yields vanadium products and reduces dependence on primary ore-linked slag alone. This recycling-linked model provides a differentiated feedstock base and can offer greater flexibility when titanomagnetite-derived slag flows shift.
Canadian-aligned operations with Brazilian processing assets emphasize primary vanadium production from dedicated mining assets, while also managing associated slag and by-product streams. Their strategic emphasis has been on stabilizing primary output, optimizing residue handling, and exploring expanded opportunities linked to slag-derived material flows. Recent production reports highlight consistent V2O5 equivalent output and continued attention to ilmenite and associated residue streams, signaling that even primary producers see slag and byproduct management as integral to overall asset efficiency. South African producers tied to Bushveld Complex operations and Central European manufacturers generating aluminothermic slag alongside ferrovanadium further illustrate the diversity of feedstock routes and processing philosophies across the market.
Recent commercial activity underscores how the landscape is evolving. Offtake term sheets covering one hundred percent of high-grade vanadium-bearing slag from proposed processing plants illustrate a move toward tightly structured supply agreements that reduce uncertainty for both producers and downstream converters. Such arrangements are especially relevant for new or expanded facilities that need committed demand to justify capital deployment. Alongside these offtake developments, ongoing production disclosures from integrated operators show that consistent output and disciplined byproduct handling remain central to maintaining competitive positioning. The trend suggests a market in which secure supply relationships, grade assurance, and processing reliability are becoming as important as raw volume.
Market structure appears to be moving through both consolidation and fragmentation pressures simultaneously. Concentration at the top reflects scale advantages in integrated steel-linked slag generation and downstream conversion, which favors larger operators that can absorb regulatory complexity, maintain processing technology upgrades, and serve demanding downstream specifications. At the same time, fragmentation persists through specialized recyclers, regional processors, and new project developers targeting particular slag grades or geographic markets. New entrants are most likely to succeed where they can offer differentiated feedstock access, advanced recovery performance, or credible offtake partnerships rather than competing purely on commodity volume.
Future Trends and Commercial Opportunities
Over the next three to five years, the vanadium slag market is likely to be shaped by three interconnected trends, each carrying clear commercial implications. The first is the continued localization of processing capacity in response to import restrictions and shifting tariff dynamics. As more jurisdictions prioritize domestic slag recovery, investment will increasingly flow toward upgraded separation lines, cleaner output streams, and integrated waste-reduction systems. Commercial opportunities will arise for technology providers, engineering partners, and operators capable of deploying modular or scalable recovery solutions that improve recovery rates while meeting local compliance requirements.
The second trend is demand diversification into energy storage and catalyst segments, which will place greater emphasis on product consistency, traceability, and specification control. While steel and alloy production will remain the largest demand base, the growth of vanadium-linked storage applications creates incremental pull for high-quality derivatives that originate from well-managed slag streams. This opens opportunities for processors that can guarantee grade stability, maintain reliable delivery schedules, and align recovery outputs with downstream refining needs. Suppliers that position themselves as consistent sources for both metallurgical and non-metallurgical channels can broaden their revenue base and reduce exposure to any single demand cycle.
The third trend is the growing strategic importance of offtake-linked project structuring and integrated supply planning. As high-grade slag streams become more closely tied to dedicated processing facilities and contracted downstream conversion, the market will reward operators that can combine production reliability with commercial certainty. This creates opportunities for partnerships that link slag producers, converters, and end users in coordinated supply frameworks, reducing price and volume uncertainty while enabling more disciplined capacity investments. At the same time, potential risks remain: regulatory changes can redirect flows suddenly, tariff adjustments can alter destination economics, and technology adoption may be uneven across regions. Feedstock variability from titanomagnetite operations and energy cost volatility can also challenge margin stability, making operational flexibility and scenario planning essential.
Actionable Insights for Decision-Makers
For manufacturers and processors, the priority is to treat slag recovery as a strategic capability rather than a residual cost center. Investing in separation efficiency, recovering more value from lower-grade streams, and building reliable offtake agreements can improve margin resilience and supply security. Aligning processing upgrades with evolving regulatory expectations also reduces compliance risk while strengthening positioning with customers that increasingly value sustainable sourcing.
For investors, the most compelling opportunities lie in businesses that combine feedstock access, processing differentiation, and credible downstream linkages. Capital deployment should favor operators with clear recovery technology roadmaps, integrated conversion pathways, or structured offtake coverage, since these attributes provide greater visibility into revenue stability and scale potential. Project-stage initiatives should be evaluated not just on resource potential but on the quality of commercial anchoring and the ability to navigate regional regulatory shifts.
For procurement and supply chain leaders, securing multi-source access and prioritizing suppliers with consistent grade performance will become increasingly important as demand diversifies and regulatory divergence affects material flows. Long-term agreements, specification alignment, and transparency around recovery and processing practices can mitigate supply disruption risk while supporting broader sustainability objectives.
Given the pace of regulatory change, evolving demand patterns, and shifting competitive dynamics, detailed segment-level intelligence remains essential for precise planning. A comprehensive research report can provide deeper breakdowns of regional dynamics, grade-specific supply behavior, application-side demand signals, and tailored scenario analysis to support more confident strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Vanadium Slag Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Combustible Gas Ir Point Detector Market Likely To Touch New Heights By End Of Forecast Period 2033
By Arjun, 2026-09-18
Combustible Gas Ir Point Detector Market
Overview
The Combustible Gas Ir Point Detector Market encompasses devices designed to detect and monitor the presence of flammable gases in various industrial environments. These detectors are vital for ensuring safety by providing early warnings of gas leaks, thus preventing potential explosions or health hazards. Their core functionalities include real-time gas concentration measurement, alarm activation, and data logging, supporting industries such as oil & gas, manufacturing, and chemical processing.
The market's growth is driven by increasing safety regulations and the need for reliable gas detection solutions. The Combustible Gas Ir Point Detector Market plays a crucial role in modern industry operations, offering precision and rapid response capabilities. These detectors are essential for compliance, worker safety, and operational continuity in environments prone to combustible gas accumulation.
Market Size and Growth
The current market value is estimated at approximately USD 1.2 billion. Over the next decade, the market is projected to reach around USD 2.5 billion, reflecting a compound annual growth rate (CAGR) of about 8%. Key growth drivers include stringent safety standards, technological advancements, and expanding industrial activities in emerging markets.
Increasing industrialization and heightened safety concerns are fueling demand for advanced detection systems. The integration of IoT and smart sensor technologies is further accelerating market expansion, making combustible gas detection more accurate and efficient.
Get free sample copy of report : https://infinitymarketresearch.com/request-sample/LPI2191
Key Drivers
• Rising safety regulations across industries
• Technological innovations in sensor technology
• Growing industrial activities in emerging markets
• Increased focus on workplace safety and compliance
Restraints
• High costs of advanced detection systems
• Technical challenges in sensor calibration and maintenance
• Regulatory delays and compliance complexities
• Operational limitations in harsh environments
Segmentation
• By Type: Fixed and Portable
• By Deployment: Indoor and Outdoor
• By Enterprise Size: Small, Medium, Large Enterprises
• By End User: Oil & Gas, Chemical, Manufacturing, Power Generation, Others
• By Region: North America, Europe, Asia-Pacific, Latin America, Middle East & Africa
Regional Insights
North America exhibits mature adoption driven by strict safety regulations and technological innovation. The U.S. and Canada lead in integrating advanced combustible gas detectors across industries.
In Europe, stringent safety standards and proactive regulatory frameworks promote steady growth, especially in the chemical and manufacturing sectors.
Asia-Pacific shows the highest growth potential, fueled by rapid industrialization, expanding infrastructure, and increasing safety awareness, particularly in China and India.
Latin America’s market is gradually expanding, with emerging industries adopting gas detection solutions amid rising safety standards.
The Middle East & Africa are witnessing growing demand driven by oil & gas exploration and refining activities, with a focus on safety compliance and operational efficiency.
Opportunities
• Adoption of IoT-enabled gas detection systems
• Development of compact, portable detectors for remote applications
• Integration with smart safety management systems
• Expanding deployment in emerging industrial sectors
• Adoption of renewable energy and green technologies
Key Companies
Honeywell International Inc.
MSA Safety Incorporated
Drägerwerk AG & Co. KGaA
Industrial Scientific Corporation
RAE Systems (a Honeywell company)
Crowcon Detection Instruments Ltd.
Senscient Inc.
Autronica Fire and Security AS
Tyco International
Yokogawa Electric Corporation
Emerson Electric Co.
Siemens AG
Conclusion
The Combustible Gas Ir Point Detector Market demonstrates strong long-term growth potential, driven by increasing safety demands and technological advancements. As industries continue to prioritize operational safety and regulatory compliance, the strategic importance of reliable gas detection solutions will expand. Overall, this market is poised for sustained expansion, offering significant opportunities for innovation and enterprise adoption.
Related Reports
Unmanned Air Vehicles Market , Size Share and Analysis | Report 2033
Industrial Boiler Feed Pumps Market , Size Share and Analysis | Report 2033
Arms Market , Size Share and Analysis | Report 2033
Temperature Cycling Test Chambers Market , Size Share and Analysis | Report 2033
High Pressure Foaming Machines Market , Size Share and Analysis | Report 2033
Ship Shore Power System Market , Size Share and Analysis | Report 2033
Electrical Systems In Ships Market , Size Share and Analysis | Report 2033
Optical Telescopic Instruments Market , Size Share and Analysis | Report 2033
Semiconductor Laser Marking Equipment Market , Size Share and Analysis | Report 2033
Portable Energy Dispersive X Ray Fluorescence Analyzers Market , Size Share and Analysis | Report 2033
About US:
We at Infinity Market Research hold expertise in providing up-to-date, authentic and reliable information across all the industry verticals. Our diverse database consists of information gathered from trusted and authorized data sources.
We take pride in offering high quality and comprehensive research solution to our clients. Our research solutions will help the clients in making an informed move and planning the business strategies. We strive to provide excellent and dedicated market research reports so that our clients can focus on growth and business development plans. We have domain-wise expert research team who work on client-specific custom projects. We understand the diverse requirements of our clients and keep our reports update based on the market scenario.
Contact US:
Pune, Maharashtra, India
Mail: Sales@infinitymarketresearch.com
Website: https://infinitymarketresearch.com/
Visit Our Research Insights: AdlerTech Labs , Infinity Researcher
Worldwide Industrial Kneader Market: What the 5.12% CAGR Shift Really Means
By PW Consulting, 2026-09-18
Global Industrial Kneader Market: Navigating Strategic Shifts and Emerging Opportunities Through 2032
The Worldwide Industrial Kneader Market has demonstrated steady expansion, with overall market size reaching approximately $1,280.5 million in 2025. From a base of $985.4 million in 2020, the sector has followed a consistent upward trajectory, reflecting the essential role of high-viscosity mixing equipment across diversified manufacturing ecosystems. Current projections indicate the market will advance at a compound annual growth rate of 5.12 percent through 2032, ultimately approaching $1,816.35 million. This growth pathway is neither linear nor automatic. It reflects converging pressures across technology, regulation, supply chain economics, and end-use demand that are actively reshaping procurement strategies, product roadmaps, and competitive positioning.
At present, the industry operates at a structural inflection point. First, raw material cost volatility has become a persistent margin constraint. U.S. hot rolled coil steel reached $1,002 per ton in early 2026, while Chinese benchmark steel prices climbed to 3,152 CNY per ton on April 29, 2026, marking a 3.28 percent year-over-year increase. Since kneader manufacturing relies heavily on structural steel, hardened alloys, and precision machining components, these input shifts directly pressure equipment pricing, lead times, and builder margins. Second, trade policy friction has reshaped cost architectures. The U.S. Section 232 steel tariffs increased to 50 percent effective June 2025, with certain exceptions remaining at 25 percent. This development imposes new cost layers on machinery manufacturers incorporating imported steel components or sourcing from affected jurisdictions, forcing rapid reevaluation of sourcing networks and pricing models. Third, demand composition is shifting. Historically anchored in rubber and plastics compounding, the market now faces a more fragmented application landscape where performance specifications, materials compatibility, and regulatory compliance vary significantly across sectors. These overlapping dynamics mean that static capacity expansion or generic equipment offerings no longer guarantee sustained relevance.
Market Structure and Concentration Dynamics
The competitive environment reflects moderate concentration, with the top three participants collectively accounting for approximately 18.45 percent of total revenue and the top five reaching 27.8 percent. This distribution signals a market where scale advantages exist but do not dominate. Regional demand is geographically dispersed, with Asia Pacific representing the largest share of activity at $515.56 million, followed by Europe at $319.86 million, North America at $278.83 million, Latin America at $103.9 million, and Mideast and Africa at $62.35 million. Application demand spans multiple end-use industries, with rubber and plastics processing at $426.24 million, chemicals and synthetics at $353.93 million, food and confectionery at $256.18 million, battery materials at $155.96 million, and pharmaceuticals and cosmetics at $88.19 million. By equipment type, sigma blade kneaders lead at $553.29 million, dispersion kneaders at $354.08 million, continuous kneaders at $238.23 million, and planetary kneaders at $134.9 million. While these figures outline the current allocation of activity, the real strategic question is how these splits will migrate as application requirements, capacity utilization, and regional manufacturing footprints evolve.
Industrial Mixer Market
Key Drivers Reshaping the Industrial Kneader Landscape
The trajectory of the industrial kneader market is no longer dictated by a single catalyst. Instead, four interlocking drivers are redefining equipment requirements, competitive advantage, and investment priorities. Understanding how these forces interact provides a clearer view of where durable growth will emerge and where legacy assumptions will fail.
Technological Innovation and Performance Differentation
Equipment performance is shifting from volume throughput toward precision, repeatability, and material adaptability. High-viscosity compounding demands tighter temperature control, reduced shear degradation, and consistent batch-to-batch uniformity. This has accelerated development of advanced cooling systems, intermesh rotor configurations, and continuous processing architectures that reduce downtime and improve energy efficiency. Recent industry activity reflects this shift. OTT RubberTech released a 2026 guide identifying top kneader mixer factories worldwide, explicitly noting that EV battery manufacturing is driving new kneader demand segments for electrode paste and high-viscosity compound processing. This signals that performance differentiation is expanding beyond traditional rubber and plastics applications into materials where particle dispersion, homogeneity, and contamination control carry direct downstream consequences. Manufacturers that can demonstrate validated processing outcomes, not just machine specifications, are gaining procurement preference in technically demanding segments.
Industrial Agitators Market
Regulatory and Trade Policy Pressures
Policy dynamics are reshaping cost structures and supply chain design. The increase in U.S. Section 232 steel tariffs to 50 percent effective June 2025, with certain exceptions remaining at 25 percent, has introduced new cost uncertainty for machinery builders relying on imported steel components. Combined with upward movement in global benchmark steel prices, this environment compels manufacturers to evaluate localized sourcing, alternative material grades, and pricing flexibility. At the same time, regulatory scrutiny across food, pharmaceutical, and cosmetics applications is raising the bar for surface finish, cleaning protocols, and material certification. Equipment that cannot meet documentation, compliance, or validation requirements faces extended sales cycles or exclusion from qualified vendor lists. The regulatory layer thus operates as both a cost pressure and a qualification filter, rewarding manufacturers with established quality systems and traceable component sourcing.
PW Consulting
Demand-Side Evolution and Application Diversification
End-use demand is broadening in both scale and technical complexity. Battery materials processing is emerging as a distinct demand pocket, driven by electrode slurry mixing, high-viscosity compound handling, and specialized formulation requirements. Simultaneously, chemicals and synthetics applications continue to seek continuous and semi-continuous kneading solutions that support higher throughput and reduced batch variability. Food and confectionery processors prioritize hygiene, easy cleaning, and material compatibility, while pharmaceutical and cosmetics manufacturers emphasize contamination control and validated processing environments. This diversification means that equipment suppliers must navigate overlapping but distinct specification sets. Procurement teams are increasingly evaluating total cost of ownership, maintenance accessibility, and integration with existing line architecture rather than relying solely on upfront equipment price. The shift favors suppliers that can map application requirements to equipment configuration with clear operational and compliance rationale.
Supply Chain and Cost Structure Reconfiguration
Input cost volatility is compelling a broader rethinking of manufacturing and delivery models. Steel price movements, combined with tariff impacts, are pressuring builders to optimize component design, standardize platforms, and selectively localize sourcing where possible. At the same time, logistics complexity and lead-time variability are influencing customer expectations around delivery reliability and aftermarket support. Suppliers that can offer modular configurations, predictable lead times, and transparent cost structures are gaining advantage in procurement negotiations. The broader implication is that cost competitiveness is increasingly defined by design efficiency, sourcing agility, and service integration rather than by labor arbitrage alone. Recent industry participation at events such as the Tire Technology Expo, where Wuxi Double Elephant Rubber & Plastics Machinery Co., Ltd. exhibited kneader products, and cooperation outreach by TF Kneader during the 2026 Spring Canton Fair, reflects ongoing efforts to align product offerings with regional demand and supply chain realities.
Competitive Landscape and Strategic Positioning
The industrial kneader market features a diverse set of established and regional participants, each pursuing distinct positioning strategies. The moderate concentration level indicates that no single player controls the market, but differentiation in technology, application focus, and service capability is increasingly decisive.
Profile of Key Participants and Strategic Orientation
Kneader Machinery Co., Ltd., based in Taiwan, has specialized since 1981 in dispersion kneaders, including standard, heavy duty, super cooling, and intermesh models tailored for rubber and plastics processing. Its long operating history and model variety position it around application-specific dispersion requirements. Farrel Pomini, operating across the USA and UK, offers internal and continuous mixers for tire, technical rubber, and high-viscosity compounding applications with capacities from 10 to 600 L, emphasizing scale flexibility and compounding precision. HF Mixing Group, headquartered in Germany, provides advanced mixing solutions including Banbury mixers and kneaders for the rubber processing industry, focusing on materials spanning high to low viscosity ranges, which aligns with performance-driven compounding markets. Kobelco, based in Japan, manufactures internal kneaders and mixing equipment for rubber and elastomer processing with emphasis on precision and durability, appealing to customers prioritizing equipment longevity and consistent mechanical performance.
Buss AG, headquartered in Switzerland, specializes in kneader technology for high-viscosity compounding in plastics, rubber, and chemical applications, targeting technically demanding processes where dispersion quality and process control are critical. Charles Ross & Son Company, based in the USA, produces kneader extruders, tilt kneaders, and sigma blade mixers for chemicals, pharmaceuticals, plastics, adhesives, and food products using German AMK technology, reflecting a cross-application portfolio supported by established engineering heritage. B&P Littleford, also USA-based, designs continuous kneaders and mixers for plastics mixing, carbon paste, and high-viscosity compounding in rubber and plastics industries, aligning with throughput and continuity requirements. Winkworth Machinery, operating in the UK since 1924, manufactures Z blade sigma kneader mixers and stainless steel industrial mixers for doughs, pastes, and high-viscosity materials, with a focus on food-grade and hygienic processing environments. Lleal, based in Spain, offers industrial kneaders for automating and optimizing kneading processes across chemical, pharmaceutical, and food sectors, emphasizing process automation and consistency. Well Shyang Machinery Co., Ltd., located in Taiwan, produces various types of kneader mixers, extruders, and pellet making machines for rubber and plastics applications, combining mixing and downstream processing capabilities. INOUE MFG., INC., based in Japan, manufactures kneading machines supporting various industries with over 100 years of experience in mixing equipment, leveraging long-standing process knowledge. PerMix, operating across USA and China, supplies sigma kneader-mixers with Z arm configuration for high-viscosity mixing in pharmaceutical, food, chemical, and other industries since 1954, positioning around cross-sector versatility and established mixer design.
Differentiation Levers and Competitive Evolution
Across this participant set, differentiation is increasingly defined by application alignment, materials expertise, and service integration rather than by equipment presence alone. Leading positions tend to emerge where suppliers can demonstrate repeatable outcomes for specific viscosity ranges, temperature profiles, and material sensitivities. Continuous and semi-continuous architectures are gaining strategic relevance as processors seek reduced batch variability and higher throughput consistency, while dispersion and sigma blade configurations remain essential where batch flexibility and wide material compatibility are required. The market is simultaneously experiencing consolidation pressure among regional players seeking broader application coverage and new entry activity from manufacturers responding to specialized demand pockets such as battery materials and high-purity processing. Recent external developments illustrate this dynamic: OTT RubberTech’s 2026 guide highlighted EV battery manufacturing as a new demand driver, while trade show participation and factory visit programs by companies such as Wuxi Double Elephant and TF Kneader reflect active efforts to expand commercial reach and technical engagement. The net effect is a landscape where technological credibility, sourcing resilience, and application-specific validation are becoming the primary filters for procurement decisions.
Forward Trends and Strategic Implications Through 2032
Looking ahead three to five years, the industrial kneader market will likely be shaped by three interconnected trends. First, demand will continue migrating toward application-specific and higher-compliance configurations. Battery materials, pharmaceutical, and food-grade processing environments are expanding specification requirements around material compatibility, cleaning validation, and process repeatability. Equipment that can meet these requirements with documented performance will capture premium positioning, while generic offerings may face margin compression. Second, continuous and semi-continuous processing is expected to gain broader adoption where throughput stability, energy efficiency, and labor optimization are prioritized. This shift will not replace batch architectures entirely but will reshape the mix of equipment types deployed across high-utilization production environments. Third, cost and sourcing resilience will remain central to competitiveness. Steel price volatility and tariff-driven cost changes will continue influencing design efficiency, platform standardization, and regional sourcing strategies. Suppliers that can balance performance, delivery predictability, and transparent cost structures will be better positioned to sustain margin health.
These trends create clear commercial opportunities for manufacturers that invest in application validation, modular design, and service integration, as well as for procurement leaders that prioritize total cost of ownership and compliance readiness. However, uncertainty remains. Demand pace in battery materials could shift with broader EV market dynamics and manufacturing scale-up patterns. Trade policy adjustments may alter cost structures further, creating winners and losers across sourcing networks. Input cost volatility and logistics variability could pressure lead times and pricing flexibility. Market participants will need to monitor these variables closely and maintain configuration agility rather than committing exclusively to narrow product assumptions.
Actionable Implications for Decision-Makers
The current trajectory suggests that strategic advantage will come from readiness, not reaction. For equipment manufacturers, the priority is to strengthen application-specific validation, optimize platform commonality to manage input cost variability, and align sourcing networks with tariff and steel price realities. Investing in continuous or semi-continuous capabilities and high-compliance configurations can open access to faster-growing, higher-specification demand pockets while reducing exposure to commoditized competition. For investors and strategic planners, the focus should be on distinguishing durable application-driven growth from cyclical capacity expansion. Segments tied to battery materials, high-viscosity chemical compounding, and hygiene-sensitive food and pharmaceutical processing warrant closer evaluation for their specification intensity and potential margin resilience, while exposure to input cost volatility and trade policy shifts should be modeled explicitly in scenario planning.
For procurement and operations leaders, the more effective evaluation framework moves beyond upfront price toward total cost of ownership, maintenance accessibility, compliance documentation, and integration compatibility. Equipment selection should weigh validated processing outcomes, cleaning and material compatibility requirements, and service responsiveness alongside throughput expectations. In an environment where raw material costs and trade conditions remain dynamic, procurement strategies that build in configuration flexibility, service coverage, and transparent cost structures are better equipped to manage uncertainty. For organizations seeking deeper segmentation data, regional procurement patterns, and tailored scenario analysis, the complete research report offers expanded detail on equipment type trajectories, application-specific growth pathways, and company-level positioning insights to support more precise strategic decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Kneader Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com